How Personal Liability Coverage Protects Homeowners
Personal liability coverage helps protect you if someone claims you caused their injury or damaged their property. In a homeowners policy, it can pay for a covered settlement or judgment and provide a legal defense, up to the policy’s terms and limits. It generally does not replace auto liability insurance or cover most business-related claims.
A guest’s fall or damage you accidentally cause to a neighbor’s property could lead to a claim. Knowing your limits and exclusions helps you choose protection that fits your risks without paying for coverage you don’t need.
I’m Shawn Beihl, and I’ve spent more than 15 years working across personal and commercial insurance. I’ll help you understand where Personal liability coverage fits, what it may leave out, and when more protection may make sense.
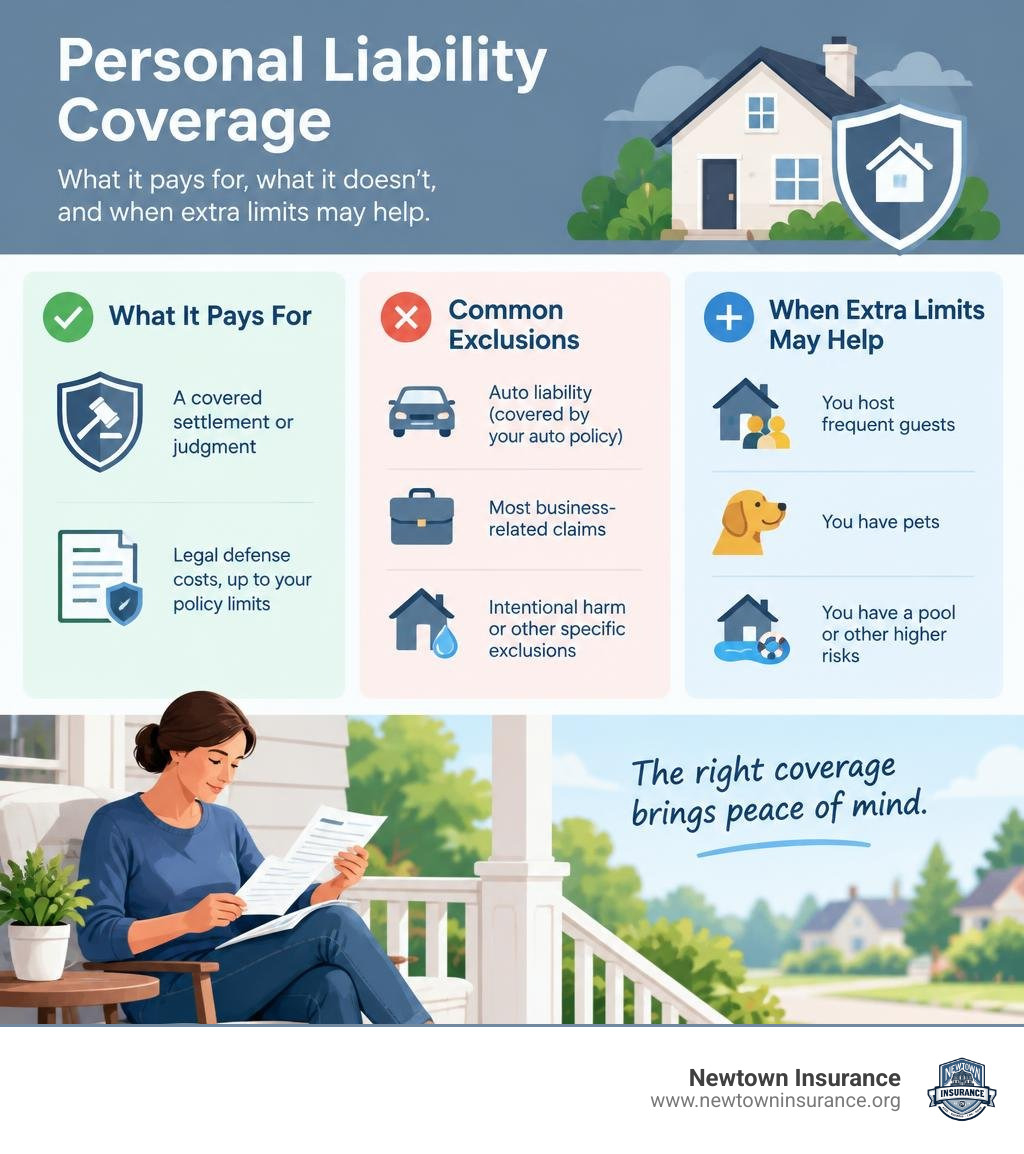
Personal liability coverage terms made easy:
What Is Personal Liability Coverage and What Does It Protect?
Legal liability is one of the most significant financial exposures any individual faces. If a delivery driver slips on your icy front steps or your child accidentally throws a baseball through a neighbor’s custom bay window, you could be held legally responsible for the resulting damages.
Personal liability insurance provides a crucial financial safety net. It steps in to pay for third-party bodily injury and property damage when you or a resident relative are deemed legally liable. Rather than paying tens or hundreds of thousands of dollars out of pocket for medical bills, structural repairs, and legal judgments, your insurer steps up to handle these costs up to your policy limit.
Crucially, this protection includes a legal defense. Defending against a lawsuit—even one that is groundless, false, or fraudulent—can cost tens of thousands of dollars in attorney fees alone. Your policy pays for these defense expenses over and above your liability limit. It also covers prejudgment interest awarded against you.
Whether your protection comes through standard homeowners forms or a Dwelling Program Personal Liability Supplement, securing robust liability insurance in PA ensures your hard-earned assets remain shielded from unexpected legal claims.
Understanding Coverage E and Key Protection Triggers
In standard homeowners policies, personal liability is formally designated as Coverage E.
Coverage E is activated by an “occurrence”—defined as an accident, including continuous or repeated exposure to substantially the same general harmful conditions, that results in bodily injury or property damage during the policy period.
When a covered incident occurs, Coverage E provides two vital benefits:
- Indemnity (Financial Settlement): Pays the damages for which you are legally liable, up to the policy limit.
- Duty to Defend: The insurer provides and pays for legal counsel to defend you in court. This defense continues until the policy limit has been fully exhausted by payment of a settlement or judgment.
While baseline policy forms historically set minimum limits at $100,000 per occurrence, most modern insurance carriers default to $300,000. In today’s litigious environment, having adequate baseline coverage is essential to prevent a single severe incident from devastating your family’s savings.
Section II Additional Benefits and Good Neighbor Coverages
Beyond standard defense and indemnity under Coverage E, Section II of your homeowners policy includes valuable additional coverages designed to resolve minor disputes and assist with administrative legal burdens.
These additional protections include:
- Claim Expenses: Covers court costs, attorney fees, bond premiums, and reasonable expenses incurred by the insured at the insurer’s request (including actual loss of earnings up to $250 per day to assist in your defense).
- First Aid Expenses: Reimburses expenses incurred for immediate first aid administered to others at the scene of an accident.
- Damage to Property of Others: Often referred to as “good neighbor” coverage, this pays up to $5,000 per occurrence for property accidentally damaged by an insured, regardless of whether you are legally at fault. For example, if your teenager accidentally breaks an expensive piece of audio equipment while visiting a friend, this feature covers the repair or replacement without requiring a formal lawsuit.
- Loss Assessment: Protects condo owners or HOA members against their share of collective liability assessments charged by the association for injuries occurring on common property.
As detailed in the HO 00 14 Homeowners 14 – Contents Comprehensive Form Part 5 Section II Analysis, modern policy forms continue to refine these coverages to match changing household needs.
Sources of Protection: How Liability Insurance Works Across Policies
Personal liability insurance does not exist in a silo; it is woven into multiple personal lines of insurance to create a comprehensive safety net. Understanding how these policies connect is fundamental to sound financial planning, as highlighted in this Property and Casualty Insurance Guide.
Standard Homeowners, Condo, and Dwelling Supplement Forms
Liability protection can be obtained through several primary contract types:
- Homeowners Forms (HO-3 / HO-5): Standard package policies for owner-occupied single-family homes that bundle dwelling coverage with personal liability.
- Condominium Unit-Owners (HO-6): Specifically tailored to unit owners, protecting interior alterations and personal liability within the unit.
- Contents Comprehensive Form (HO-14): Modern renters and contents forms providing broad personal liability protection for mobile households and tenants.
- Landlord Policies (DP-1 / DP-3): Dwelling programs for rental or tenant-occupied properties where premises liability can be added via endorsement.
- Comprehensive Personal Liability (CPL): A standalone (monoline) policy that offers up to $1M in personal liability coverage without being tied to a primary property package—ideal for individuals who rent or hold unique real estate arrangements.
Evaluating Personal Liability Coverage Exclusions and Restrictions
While personal liability coverage is broad, it is not all-encompassing. Standard ISO forms contain distinct exclusions designed to prevent personal policies from covering commercial risks, intentional wrongdoing, or hazards governed by other specialized policies.
Before assuming a loss is covered, it is wise to consult our Personal Indemnity Guide 2026 and note these primary exclusions:
- Business Pursuits: Activities related to a profession, trade, or commercial occupation conducted from the home are excluded unless specifically endorsed.
- Intentional Injury or Damage: Expected or intended harm caused by an insured is strictly excluded (with exceptions for reasonable actions taken to protect persons or property).
- Motor Vehicles: Liability arising from cars, trucks, and registered road vehicles is excluded and must be handled by an auto policy. (Exceptions exist for golf carts on golf courses, maintenance equipment like lawn mowers, assistive devices, and battery-powered toys operating under 5 mph).
- Watercraft and Aircraft: Certain high-powered boats, jet skis, and all aircraft (including hobbyist drones over certain weight limits) are excluded.
- Communicable Diseases and Controlled Substances: Transmitting illnesses or illegal drug-related liabilities are entirely excluded (prescriptions from licensed healthcare professionals are covered).
- Workers’ Compensation: Injuries to domestic employees who are legally eligible for state statutory workers’ compensation benefits are excluded.
Coverage E vs. Coverage F: Distinguishing Legal Liability from Medical Payments
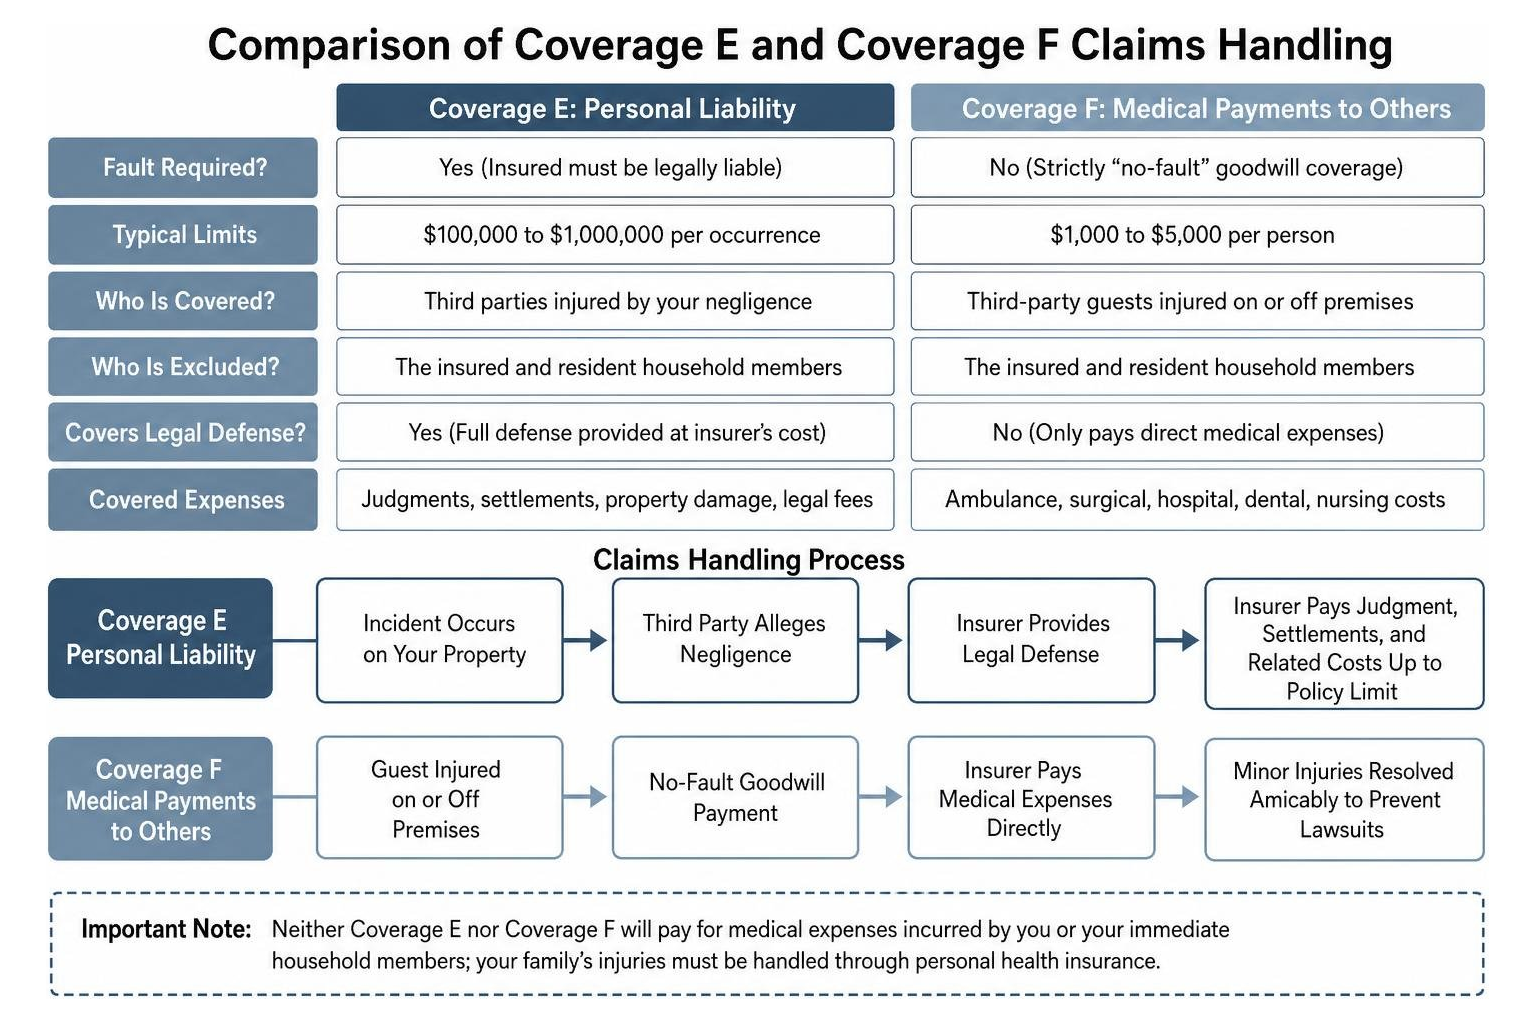
Homeowners insurance packages Section II into two distinct components: Coverage E (Personal Liability) and Coverage F (Medical Payments to Others). A common point of confusion is how these two sections interact when a visitor is hurt.
| Policy Feature | Coverage E: Personal Liability | Coverage F: Medical Payments to Others |
|---|---|---|
| Fault Required? | Yes (Insured must be legally liable) | No (Strictly “no-fault” goodwill coverage) |
| Typical Limits | $100,000 to $1,000,000 per occurrence | $1,000 to $5,000 per person |
| Who Is Covered? | Third parties injured by your negligence | Third-party guests injured on or off premises |
| Who Is Excluded? | The insured and resident household members | The insured and resident household members |
| Covers Legal Defense? | Yes (Full defense provided at insurer’s cost) | No (Only pays direct medical expenses) |
| Covered Expenses | Judgments, settlements, property damage, legal fees | Ambulance, surgical, hospital, dental, nursing costs |
Key Differences Between Personal Liability and Guest Medical Payments
Coverage E is designed for serious legal disputes where fault must be proven. If someone alleges that your failure to repair a broken railing caused their fall, Coverage E provides your legal defense and pays any resulting judgment up to your policy limit.
In contrast, Coverage F is a fast, goodwill remedy for minor injuries. If a guest pinches their finger in your heavy front door or trips on a rug, Guest Medical Coverage pays for their urgent medical bills—such as X-rays, stitches, dental work, or ambulance transportation—without assigning blame. It is designed to resolve minor accidents amicably before they escalate into formal lawsuits.
That neither Coverage E nor Coverage F will pay for medical expenses incurred by you or your immediate household members; your family’s injuries must be handled through personal health insurance.
Policyholder Duties and Actions Required After an Occurrence
If an accident occurs on your property, your policy requires you to fulfill specific duties to maintain your coverage. Failing to comply with these policy conditions can compromise your insurer’s ability to defend you and potentially jeopardize your claim.
- Provide Prompt Written Notice: Notify your insurance agent or carrier immediately with details regarding the time, place, circumstances, and names of any injured parties and witnesses.
- Document the Scene: Take photographs of the area and keep records of what transpired while memories are fresh.
- Forward All Legal Papers: Send your insurer copies of every notice, demand, summons, or legal document you receive related to the incident.
- Cooperate Fully: Assist the insurer in making settlements, conducting suits, enforcing indemnity rights, and attending hearings.
- Do Not Make Voluntary Payments: Never admit fault or make unauthorized payments to an injured party (outside of reasonable first aid at the time of the accident), as this can compromise the legal defense.
Expanding Your Protection with Personal Umbrella Excess Liability
In severe liability cases—such as a catastrophic swimming pool injury, a multi-car pileup, or a dog bite resulting in permanent impairment—medical bills and legal judgments can easily soar past the standard $300,000 homeowners limit. When your base policy limit is exhausted, your personal assets, investments, and future wages are directly vulnerable.
This is where a Personal Umbrella Excess Liability policy becomes essential. An umbrella policy acts as a second tier of protection, sitting above your auto, homeowners, and watercraft policies. Once underlying limits are paid out, the umbrella policy steps in to cover the remaining balance in increments of $1 million up to $5 million.
In addition to expanding your financial ceiling, umbrella policies offer broader coverage, often filling gaps by defending against claims like libel, slander, false arrest, or invasion of privacy. To learn more about this essential tier of security, review whether an umbrella insurance policy is worth the cost and explore our dedicated options for umbrella insurance in Newtown, PA.
Determining How Much Personal Liability Coverage You Need in 2026
When calculating your liability requirements, evaluate your total financial exposure:
- Home equity and real estate holdings
- Retirement savings and brokerage accounts
- Future earning potential
- Risk factors (e.g., swimming pools, trampolines, teenage drivers, dog breeds, frequent entertaining)
Despite the clear benefits of excess protection, a J.D. Power study revealed that only 22% of US homeowners with incomes between $100,000 and $200,000 carry an umbrella policy. Leaving your household exposed to modern legal awards is a significant risk.
For a straightforward breakdown of costs and coverage options, read our guide on personal liability insurance quotes explained without the headache.
Underlying Policy Limits and Umbrella Qualification Rules
Umbrella policies are excess policies, meaning they require robust underlying liability foundations to prevent minor claims from reaching the excess tier. To qualify for an umbrella policy, insurance carriers mandate that your base policies maintain specific minimum limits:
- Homeowners Premises Liability: Minimum $300,000 (Coverage E)
- Auto Bodily Injury Liability: Minimum $250,000 per person / $500,000 per accident
- Auto Property Damage Liability: Minimum $100,000 per accident
State motor vehicle minimums (such as Pennsylvania’s statutory minimums outlined in the Pennsylvania Driver and Vehicle Services Insurance Overview) are not sufficient to qualify for umbrella protection. Bundling your home, auto, and umbrella policies with a single carrier ensures seamless coverage and prevents coverage gaps between your base and excess policies.
Frequently Asked Questions About Homeowner Liability Protection
Does personal liability insurance cover short-term rentals or Airbnb hosting?
Standard homeowners policies contain strict business exclusions, but ISO forms (such as the HO 00 14) provide an exception for home-sharing host activities when the rental is occasional and used strictly as a residence.
However, if you rent out your property frequently, host on a commercial scale, or manage multiple short-term rentals, standard personal liability will not provide adequate protection. In those situations, you need a dedicated home-sharing endorsement or a specialized commercial landlord policy to avoid claim denials.
How does individual liability insurance interact with auto and watercraft policies?
Personal liability under a homeowners policy specifically excludes motor vehicles and powered watercraft. Each policy line serves as the primary defense for its designated domain:
- Auto Accidents: Covered exclusively by your auto insurance liability limits. For more information, check our Personal Vehicle Insurance Guide 2026.
- Boating Accidents: Covered by specialized watercraft liability policies.
- Home and General Personal Activities: Covered by homeowners or CPL policies.
Your personal umbrella policy sits atop all of these primary policies, providing excess coverage across auto, water, and home claims once primary limits are exhausted.
What is the difference between personal liability and comprehensive personal liability?
Personal liability is typically bundled directly into a standard package policy (like an HO-3 or HO-6) alongside property damage coverage for your dwelling and belongings.
Comprehensive Personal Liability (CPL) is a standalone, monoline liability policy. It provides identical bodily injury and property damage defense for individuals who do not own a traditional home package—such as long-term apartment renters, landholders with vacant lots, or property investors. For personalized policy comparisons, consult our Personalized Insurance Guide 2026.
Conclusion
Protecting your home is about more than insuring its physical structure; it is about shielding your family’s financial future from unpredictable legal claims. Accidents happen in an instant, and without adequate personal liability and umbrella coverage, a single lawsuit can jeopardize everything you have worked to build.
At Newtown Insurance, we provide Pennsylvania residents with clear advice, transparent pricing, and tailored protection designed to eliminate dangerous coverage gaps without overpaying.
Take the next step in securing your household by connecting with Shawn Beihl and our dedicated team today to build tailored homeowner protection that gives you true peace of mind.