
How Uninsured Motorist Coverage Works in Pennsylvania
Pennsylvania drivers can buy uninsured motorist (UM) coverage to help pay for injuries caused by a driver with no insurance or a hit-and-run driver. Underinsured motorist (UIM) coverage applies when the at-fault driver has insurance, but not enough to cover your losses. Pennsylvania law requires insurers to offer both coverages, but you can reject them in writing. They are not required purchases.
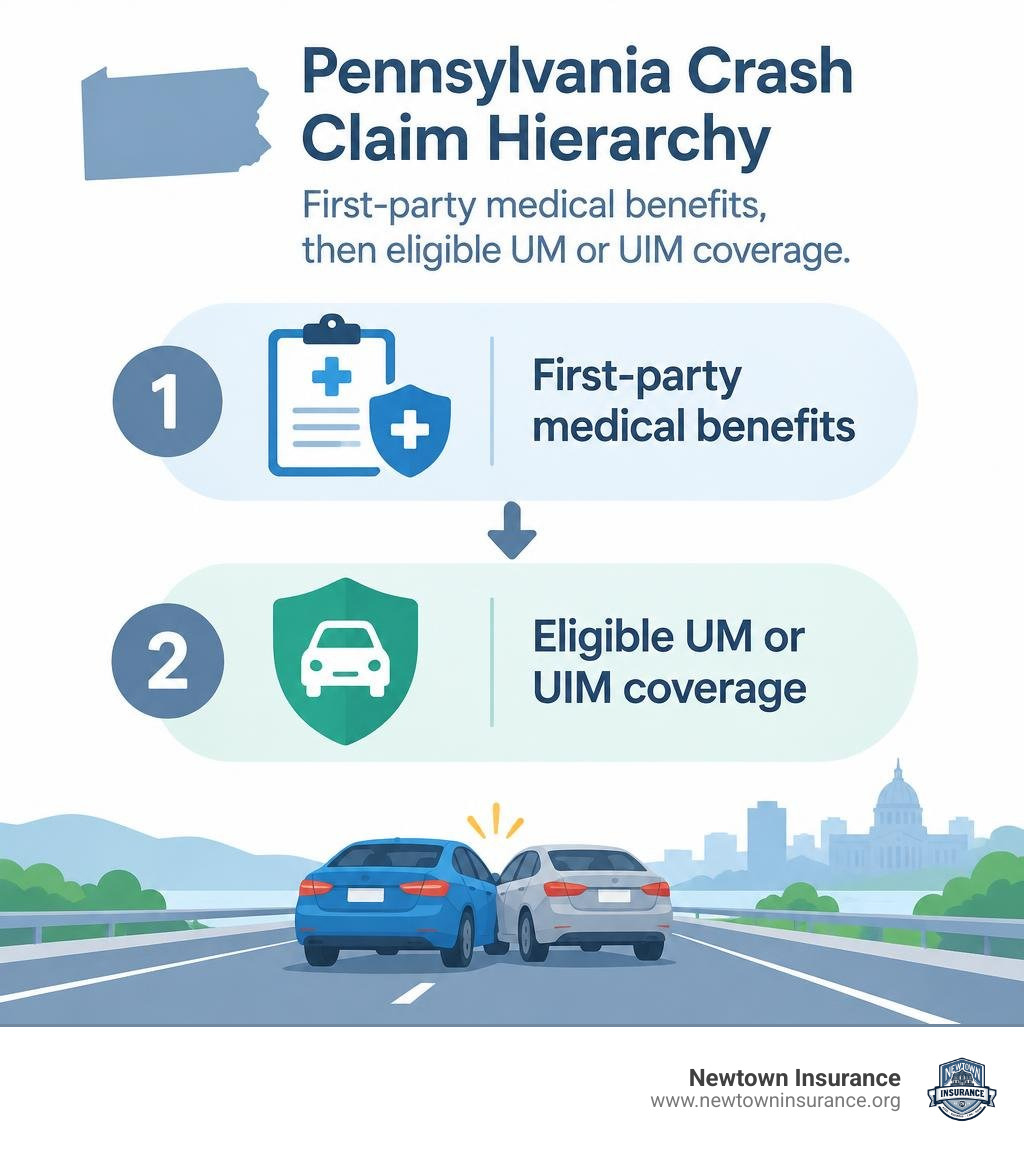
After a crash, your own first-party medical benefits generally pay eligible medical bills first. UM or UIM coverage may then help with other eligible losses, up to your policy limits. An estimated 6% of Pennsylvania drivers are uninsured, compared with about 13% nationwide.
I’m Shawn Beihl at Newtown Insurance, and my 15-plus years in specialty insurance inform how I explain uninsured motorist PA coverage. My goal is to help you weigh the protection against its cost.
Easy uninsured motorist pa word list:
Legal Rules and Requirements for Uninsured Motorist PA Coverage
Navigating the rules of the road in the Commonwealth of Pennsylvania means understanding how state statutes protect your financial well-being after a serious collision. Under the Pennsylvania Motor Vehicle Financial Responsibility Law (MVFRL), every driver must maintain a baseline policy that meets standard state requirements.
To legally register and operate a passenger vehicle, you must carry minimum liability coverage in the following amounts:
- $15,000 for bodily injury to one person in a single accident
- $30,000 for bodily injury to two or more people in a single accident
- $5,000 for property damage caused to another party’s vehicle or property
While these liability baselines protect other motorists when you are at fault, they do nothing to cover your own hospital visits, physical therapy, or vehicle repairs when an uninsured driver hits you. To safeguard yourself, Pennsylvania established specific statutory guidelines regarding optional protections in Section 1731.0 – Title 75 – VEHICLES. Reviewing standard auto insurance requirements in Pennsylvania ensures that you balance state-mandated coverage with essential personal protections.
Mandatory Insurer Offer and Written Rejection Rules
In Pennsylvania, insurance companies cannot simply skip over uninsured motorist coverage when issuing a policy. Under 75 Pa. C.S. § 1731, insurance carriers are strictly mandated to offer both uninsured motorist (UM) and underinsured motorist (UIM) coverages in amounts equal to your selected bodily injury liability limits.
However, purchasing this protection is not mandatory. If you choose not to carry it, the law requires strict administrative compliance:
- The Rejection Must Be in Writing: An insurer cannot decline coverage on your behalf through a phone conversation or casual verbal agreement.
- Standardized Statutory Language: The waiver form must match the exact phrasing provided by Pennsylvania statute. The form clearly notifies you that you are giving up critical financial protections for yourself and resident household members.
- Separate Signature Pages: The rejection cannot be buried inside standard policy paperwork. It must exist on a distinct, separate form signed and dated by the first named insured.
If an insurance company fails to secure a properly executed, legally compliant rejection form, the law treats that waiver as void. In such cases, your policy automatically defaults to providing uninsured motorist coverage equal to your bodily injury liability limits. For an in-depth breakdown of state policy structures, explore our comprehensive Pennsylvania auto insurance guide.
How Uninsured Motorist PA Policies Protect Against Hit-and-Run Drivers
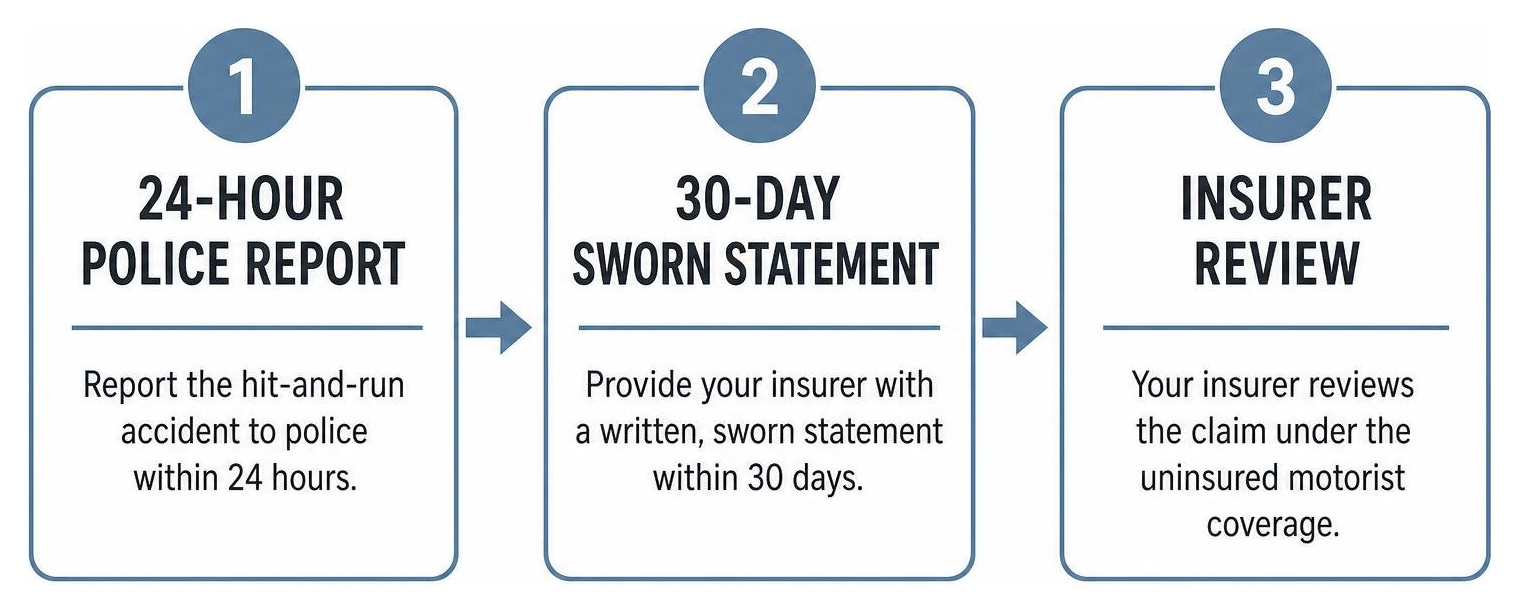
A hit-and-run crash—often referred to in insurance policies as an encounter with an unidentified or “phantom vehicle”—is treated under Pennsylvania law as an uninsured motorist claim. If an unknown driver strikes your car and speeds away, you cannot file a third-party claim against their insurance carrier because their identity remains unknown.
To access your UM benefits after a hit-and-run incident under state regulations detailed in CHAPTER 63. UNINSURED MOTORISTS COVERAGE, you must follow specific procedural rules:
- Prompt Police Notification: You must report the accident to the local police department or Pennsylvania State Police within 24 hours of the collision.
- Written Sworn Statement: You must provide your insurance carrier with a formal, sworn statement detailing the crash within 30 days of the incident.
- Physical Contact Requirements: Standard policy terms generally require actual physical contact between the unidentified vehicle and your car to confirm an accident occurred and discourage fraudulent claims.
Uninsured vs. Underinsured Motorist Protection in Pennsylvania

While uninsured motorist (UM) and underinsured motorist (UIM) protections are frequently grouped together, they address fundamentally different financial scenarios on the road.
- Uninsured Motorist (UM) Coverage: Steps in when the at-fault driver has no auto liability insurance whatsoever, when their insurance carrier denies coverage or becomes insolvent, or when you are the victim of a hit-and-run accident.
- Underinsured Motorist (UIM) Coverage: Activates when the at-fault driver carries insurance, but their liability limits are insufficient to fully pay for your total medical bills, lost income, and long-term recovery costs.
Consider a real-world scenario: An at-fault motorist carries only Pennsylvania’s minimum bodily injury liability limit of $15,000. If your emergency surgery and rehabilitation total $85,000, the at-fault driver’s policy is exhausted immediately after paying $15,000. Your underinsured motorist coverage steps in to cover the remaining $70,000 gap, up to your purchased UIM limit. Learning why underinsured motorist protection is essential helps prevent devastating out-of-pocket costs after high-impact crashes.
Comparing UM and UIM Benefits
The table below highlights the operational differences between these two coverages:
| Coverage Feature | Uninsured Motorist (UM) | Underinsured Motorist (UIM) |
|---|---|---|
| At-Fault Driver Status | Has zero liability insurance or flees scene | Carries insurance, but limits are exhausted |
| Primary Trigger | Total absence of an enforceable third-party policy | Damages exceed the at-fault driver’s policy limits |
| Hit-and-Run Coverage | Yes (subject to prompt police and insurer notice) | No (requires identified driver and active policy) |
| First-Party Payment Order | Pays after your mandatory medical PIP benefits | Pays after third-party liability limits are fully paid |
| Default Policy Limit | Matches your bodily injury liability limit | Matches your bodily injury liability limit |
Stacking Options for Uninsured Motorist PA Claims
Stacking is one of the most powerful features of Pennsylvania auto insurance law under 75 Pa. C.S. § 1738. Stacking allows you to combine the UM or UIM coverage limits across multiple vehicles on a single policy, or across multiple policies within the same household, substantially expanding your total available compensation.
Pennsylvania recognizes two distinct forms of stacking:
- Intra-Policy Stacking: Combining coverage limits across multiple vehicles listed on the same insurance policy. For instance, if you insure three cars on one policy and carry $50,000 in UM bodily injury coverage per vehicle, stacking allows you to access up to $150,000 in total coverage for a single incident.
- Inter-Policy Stacking: Combining coverage limits from distinct, separate policies within the same household (such as your personal auto policy and a spouse’s or parent’s separate auto policy).
By default, Pennsylvania law applies stacked coverage to your policy. To remove stacking and lower your premium, you must sign a specific statutory waiver.
Over the years, Pennsylvania appellate courts have repeatedly refined stacking rules. Significant rulings have struck down broad policy restrictions, such as certain household vehicle exclusions that previously prevented policyholders from stacking benefits across household policies. Unless a carrier can produce an unblemished, fully compliant § 1738 waiver, stacked coverage remains in effect.
How Pennsylvania’s No-Fault System and Tort Selections Impact Your Claim
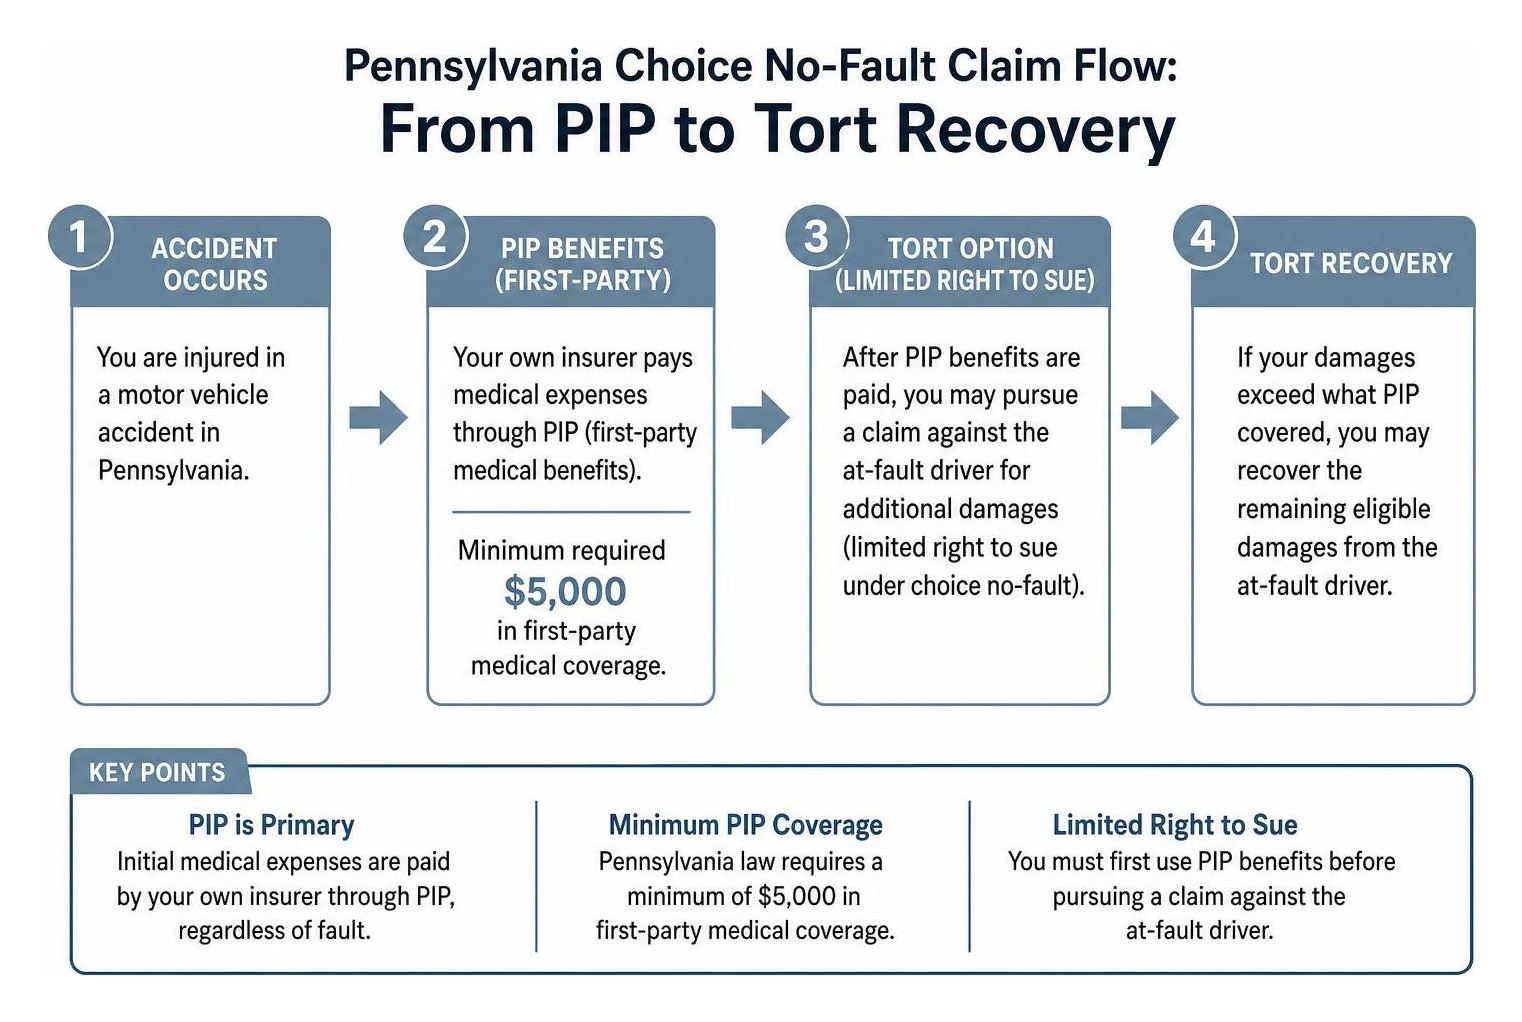
Pennsylvania operates under a “choice no-fault” insurance framework. This system dictates how your medical bills are handled following a crash, regardless of who caused the collision.
PIP Benefits and Initial Medical Coverage
Under Pennsylvania’s no-fault rules, your initial medical expenses are paid by your own insurer through Personal Injury Protection (PIP), officially known as first-party medical benefits.
- Pennsylvania law requires a minimum of $5,000 in first-party medical coverage.
- These medical benefits apply immediately, paying doctors and hospitals directly without waiting to establish fault.
- If your medical expenses exceed your selected PIP limits, your uninsured or underinsured motorist coverage steps in to pay remaining medical balances, future rehabilitation expenses, and lost wages.
Full Tort vs. Limited Tort Restrictions
When establishing your auto policy, Pennsylvania requires you to choose between two tort options:
- Full Tort Option: Grants you unrestricted rights to seek compensation from an at-fault driver (or through your own UM/UIM policy) for both financial losses (medical bills, lost earnings) and non-economic damages (pain, suffering, and emotional distress), regardless of how minor or severe the injury may be.
- Limited Tort Option: Lowers your monthly premium in exchange for waiving your right to recover non-economic damages (pain and suffering), unless your injuries meet the statutory definition of a “serious injury.” Pennsylvania law defines a serious injury as one resulting in death, serious impairment of a bodily function, or permanent serious disfigurement.
Your tort selection follows you directly into an uninsured motorist claim. If you select limited tort on your policy, you cannot collect pain and suffering compensation from your UM coverage unless your injuries meet the serious injury threshold or qualify for specific statutory exceptions (such as being hit by a driver operating an out-of-state registered vehicle). Selecting full tort auto insurance gives you complete legal protection, preserving your right to recover full compensation for pain and suffering without restrictive injury thresholds.
Navigating UM Claims: Deadlines, Insurer Tactics, and Recovery Steps

Filing a claim against your own insurance company can feel counterintuitive. Although you pay your premiums on time, the insurance company’s claims department will carefully evaluate every dollar requested under uninsured motorist coverage.
Immediate Actions After an Accident
To ensure your claim proceeds smoothly, follow these practical steps immediately following a collision:
- Contact Emergency Services: Request local police or state troopers immediately. A formal police crash report is critical evidence, especially for hit-and-run events.
- Gather Scene Evidence: Take wide-angle and close-up photographs of vehicle damage, road conditions, skid marks, traffic signs, and any visible physical injuries.
- Collect Witness Details: Secure names, phone numbers, and brief recorded or written statements from any independent eyewitnesses.
- Seek Immediate Medical Attention: Go to an emergency room, urgent care clinic, or your primary physician right away. Gaps in treatment can weaken your claim.
- Notify Your Insurer Promptly: Inform your insurance provider that an accident occurred, but avoid giving definitive recorded statements about injury severity until you have fully consulted your medical providers.
Statute of Limitations and Policy Timelines
Understanding Pennsylvania legal deadlines is essential to preserving your right to financial recovery:
- Tort Lawsuit Limitation (42 Pa. C.S. § 5524): If you are filing a direct personal injury lawsuit against an at-fault driver, Pennsylvania enforces a strict two-year statute of limitations from the date of the accident.
- UM/UIM Contract Limitation (42 Pa. C.S. § 5525): Because a claim against your own uninsured motorist policy is a first-party contract claim, Pennsylvania applies a four-year statute of limitations. This four-year clock generally begins when the insurance company formally breaches the contract (for example, by denying coverage or offering an unreasonably low settlement), rather than on the date of the collision itself.
Despite the statutory four-year window for contract actions, your auto policy contains contractual notification rules that require you to report claims promptly—often within 30 days for hit-and-run incidents.
Overcoming Insurer Pushback and Settlement Delays
When you submit an uninsured motorist claim, your insurance provider effectively steps into the shoes of the at-fault driver. Common tactics used during settlement negotiations include:
- Disputing Medical Causation: Arguing that your injuries are tied to pre-existing conditions rather than the recent car crash.
- Downplaying Injury Severity: Claiming that your recovery was swift and that ongoing treatments or physical therapy sessions are unnecessary.
- Issuing Early Lowball Offers: Offering a quick, nominal payout before the full extent of your long-term medical care is known.
- Mandatory Arbitration Demands: Many Pennsylvania auto policies include mandatory arbitration clauses for UM/UIM claims, meaning disputes are resolved by a panel of arbitrators rather than a jury trial.
Documenting all medical bills, keeping a daily symptom journal, and working with experienced professionals ensures your claim receives a fair and thorough evaluation.
Frequently Asked Questions About Pennsylvania UM Coverage
Will My Insurance Rates Increase If I File a Not-at-Fault UM Claim?
Under Pennsylvania law (75 Pa. C.S. § 1799.3), auto insurance companies are generally prohibited from assessing premium surcharges or increasing your rates simply because you filed a claim for an accident in which you were not at fault. Because uninsured motorist claims are filed when another driver causes the crash, your carrier cannot legally penalize you for using the coverage you purchased.
Understanding how state consumer protections interact with car insurance rates in Pennsylvania helps you make confident coverage decisions without fear of rate penalties.
What Legal Options Exist If You Lacked UM Coverage?
If you rejected UM coverage and were injured by an uninsured driver, your options for financial recovery become significantly narrower:
- Direct Civil Lawsuit: You can file a personal injury lawsuit directly against the uninsured driver. However, drivers without auto insurance frequently have minimal personal assets or income, making civil judgments difficult or impossible to collect.
- Criminal Restitution: If the at-fault driver is criminally prosecuted for hit-and-run or driving without insurance, the sentencing judge may order restitution payments, though these are typically paid in small installments over many years.
- Health Insurance Coverage: Your private health insurance or employer-sponsored medical plan will cover necessary medical treatments once your first-party PIP medical limit ($5,000 minimum) is exhausted, though health insurers may place a subrogation lien on any future settlements.
What Damages Can Be Recovered Through UM Benefits?
Uninsured motorist coverage is designed to compensate you for the damages you would have legally recovered from the at-fault driver had they carried adequate liability insurance:
- Outstanding Medical Costs: Hospital bills, surgery fees, rehabilitation, physical therapy, prescription medications, and expected future medical care.
- Lost Wages: Reimbursement for income lost while recovering away from work.
- Diminished Earning Capacity: Compensation if physical limitations prevent you from returning to your prior profession or earning level.
- Pain and Suffering: Compensation for physical pain, emotional distress, and loss of life’s pleasures (subject to your Full Tort or Limited Tort policy selection).
- Loss of Consortium: Compensation for the negative impact the injuries have had on your marital relationship.
Conclusion
Carrying reliable uninsured and underinsured motorist coverage is one of the most effective ways to protect your household from unpredictable road hazards across Pennsylvania. While state law establishes minimum liability limits, those baseline figures leave substantial gaps when serious accidents happen. Reviewing your policy selections, evaluating stacking opportunities, and securing full tort coverage ensure you never have to carry the financial burden of another driver’s negligence.
At Newtown Insurance, we provide clear guidance, transparent pricing, and personalized policy reviews tailored to Pennsylvania drivers. Whether you are updating your existing policy or exploring customized protection options, our team is here to help you secure complete peace of mind on the road. Connect with our team today to explore tailored coverage options and request a personalized policy review through our insurance services portal.