
Compare Car Insurance Quotes in Bristol, PA, Without Guesswork
Get quotes from several insurers using the same coverage limits, deductible, and driver details. That gives you a fair price comparison. Check each quote’s medical benefits, uninsured motorist coverage, and tort option before choosing the lowest premium. Pennsylvania’s minimum coverage may cost less, but it can leave you with more to pay after a crash.
Your rate will depend on your driving record, vehicle, coverage choices, and available discounts. Comparing like-for-like car insurance quotes in Bristol PA is the clearest way to spot savings without giving up protection you need. According to the Pennsylvania Insurance Department, drivers should review coverage options annually because rates and personal circumstances change over time.
I’m Shawn Beihl of Newtown Insurance, with more than 15 years of experience in insurance and risk advice. I help drivers compare car insurance quotes in Bristol, PA, with an eye on both today’s price and long-term costs.
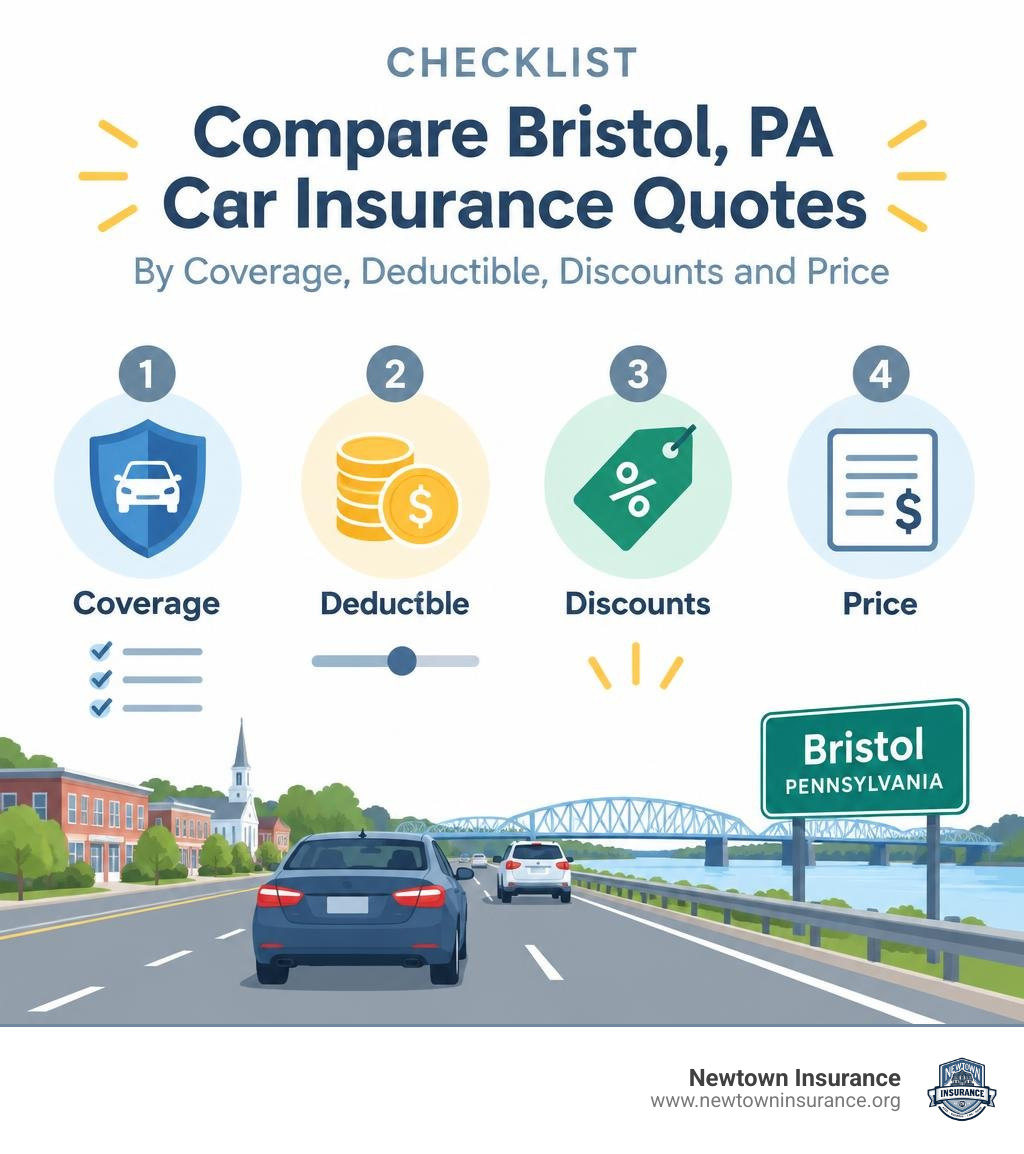
Know your car insurance quotes in bristol pa terms:
Understanding Factors That Drive Car Insurance Quotes in Bristol PA
Living along the Delaware River in historic Bucks County offers plenty of charm, but navigating local roads comes with distinct financial realities for vehicle owners. When insurers calculate your premium in Bristol, they evaluate far more than your vehicle’s make and model. They look closely at localized risk variables that affect accident frequency, repair costs, and claim severity across our corner of Pennsylvania.
One of the largest factors is regional traffic density. Bristol sits at a bustling crossroads between Philadelphia, Trenton, and the broader Lower Bucks County corridor. Daily commuter traffic along major arteries like Route 13, the Pennsylvania Turnpike (I-276), and Interstate 95 significantly elevates collision probability compared to rural areas. Stop-and-go congestion and complex highway interchanges mean minor fender benders and multi-vehicle collisions occur more frequently here. Drivers in neighboring communities face similar trends, as detailed in our guide covering car insurance in Levittown, PA.
Beyond traffic volumes, several key local variables shape your rate:
- Uninsured Driver Rates: Approximately 15% of drivers in Bristol operate vehicles without active insurance. When an uninsured driver causes a crash, insurance companies often must absorb costs through uninsured motorist coverage, which raises baseline risk pools for everyone in the area.
- Accident and Claim Frequency: Dense intersections along Bristol Pike and Green Lane experience higher claim frequency, prompting carriers to adjust territorial risk factors.
- Winter Weather and Environmental Hazards: Freezing rain, snowstorms, and road salt cause slippery winter roads and gradual vehicle wear, increasing seasonal comprehensive and collision claims.
- Vehicle Theft and Vandalism Statistics: Comprehensive premiums reflect neighborhood-level property crime rates, including stolen vehicles and catalytic converter theft.
- Credit-Based Insurance Scoring: In Pennsylvania, carriers frequently utilize insurance credit scores to assess risk, meaning your credit tier directly shifts your baseline rate.
Overall, auto coverage in Bristol costs roughly 10% more than the national average due to local traffic patterns, roadway density, and localized claim volumes.
Pennsylvania Coverage Minimums vs. Full Coverage in Bristol
Every Pennsylvania driver must maintain basic legal coverage, but meeting state minimums does not guarantee you are adequately protected against financial loss. The Commonwealth mandates specific liability thresholds:
- $15,000 for bodily injury per person
- $30,000 for bodily injury per accident
- $5,000 for property damage liability
- $5,000 for first-party medical benefits
While buying minimum liability keeps you street-legal, an accident on I-95 involving modern vehicles can surpass a $5,000 property damage limit in seconds. If you total another driver’s new SUV, you are personally on the hook for any balance beyond that $5,000 threshold.
To help clarify these critical state-specific rules, we have put together The Keystone State Guide to Getting Your Best Auto Insurance Quote Ever!, which breaks down legal requirements and optional coverages across Pennsylvania.
| Coverage Feature | PA State Minimum Policy | Full Coverage Policy |
|---|---|---|
| Bodily Injury Liability | $15,000 per person / $30,000 per accident | $100,000 per person / $300,000 per accident (or higher) |
| Property Damage Liability | $5,000 limit | $50,000 to $100,000+ limit |
| First-Party Medical | $5,000 required minimum | $10,000 to $25,000+ optional limit |
| Collision Coverage | Not included | Included (covers damage to your car after a crash) |
| Comprehensive Coverage | Not included | Included (theft, vandalism, weather, animal strikes) |
| Uninsured/Underinsured Motorist | Optional (often rejected on basic policies) | Recommended (protects you if hit by an uninsured driver) |
| Tort Option | Typically defaulted to Limited Tort | Choice of Limited Tort or Full Tort |
A major decision facing Pennsylvania motorists is selecting between Limited Tort and Full Tort. Choosing Limited Tort saves you roughly 15% on your premium, but you give up the legal right to sue an at-fault driver for non-monetary damages (such as pain and suffering) unless your injuries meet the state’s legal threshold for “serious impairment of body function.” Full Tort preserves your unrestricted right to seek recovery for pain and suffering, regardless of injury severity.
Practical Strategies to Lower Your Auto Premiums
Finding affordable coverage in Bristol does not mean stripping away vital protection. You can lower your annual costs by adopting proactive policy strategies and comparing options effectively.
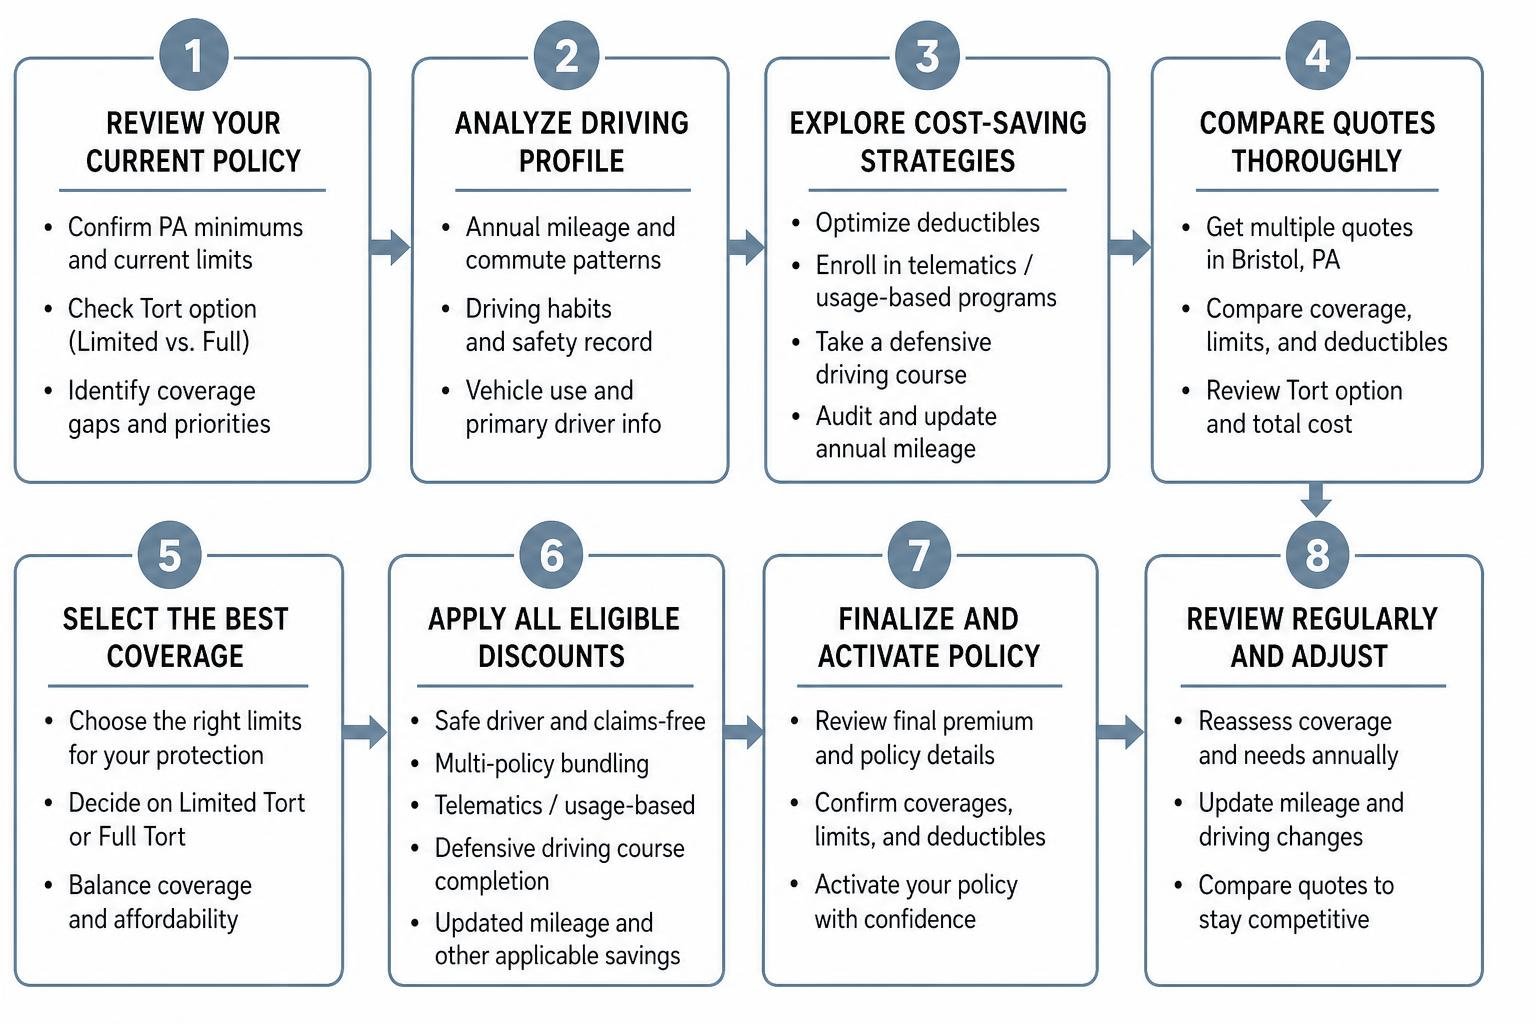
- Optimize Your Deductibles: Raising your comprehensive and collision deductibles from $250 or $500 to $1,000 can lower your physical damage premiums by 10% to 25%. Ensure you keep that deductible amount readily accessible in an emergency fund.
- Enroll in Telematics / Usage-Based Programs: If you commute short distances or maintain safe driving habits, telematics apps and plug-in devices track braking, speed, and mileage to deliver savings up to 30%.
- Audit Annual Mileage: If your daily routine has shifted toward remote work or carpooling, updating your annual estimated mileage can reduce your premium.
- Take a Defensive Driving Course: Mature drivers and young operators can often secure a multi-year premium discount by completing a state-approved defensive driving class.
- Shop and Compare Thoroughly: Rates change frequently as insurers update their underwriting guidelines. Our complete guide to comparing insurance quotes outlines how to review market options without sacrificing essential limits.
Evaluating Safe Driver and Policy Bundling Discounts
Insurers provide substantial savings for households that combine multiple insurance policies under one roof.
- Multi-Policy Bundling: Pairing your auto policy with a homeowners, renters, or condo policy can reduce overall premiums by 10% to 20%.
- Multi-Vehicle Discounts: Insuring two or more household cars on the same policy earns a lower per-vehicle rate.
- Claims-Free / Safe Driver Rewards: Maintaining an accident-free record for three to five consecutive years qualifies you for prime tier rates.
- Good Student Discounts: Full-time students on your policy who maintain a B average (3.0 GPA) or higher can earn savings of up to 15%.
- Automatic Payment and Paperless Billing: Small administrative discounts apply when you set up electronic funds transfers and paperless policy documents.
How Credit and Driving Records Influence Car Insurance Quotes in Bristol PA
Your driving history and credit profile are two of the most influential factors determining your premium. In Bristol, drivers with clean driving records save up to 30% compared to motorists who have a single at-fault accident or moving violation on record.
Insurers view tickets for speeding, reckless driving, or running red lights as indicators of future loss risk. An at-fault crash typically carries a policy surcharge that stays on your premium for three to five years. Maintaining continuous coverage is equally critical; even a brief lapse in insurance can place you in a high-risk category and trigger significant penalties.
Credit-based insurance scores also play a substantial role in Pennsylvania. Actuarial data shows a statistical link between credit stability and claim frequency. Drivers with excellent credit scores frequently secure lower rates than drivers with identical driving records who have lower credit scores. For a clear look at how your specific profile translates into real pricing, exploring personalized insurance quotes helps identify which insurers offer the best rates for your unique background.
Common Mistakes When Evaluating Local Insurance Policies
Navigating the auto insurance market can feel overwhelming, leading many drivers to make costly oversights when buying or renewing coverage.
- Buying for Price Alone: Choosing the absolute cheapest quote often means accepting bare-bones liability, high deductibles, and zero roadside assistance or rental reimbursement.
- Relying Exclusively on State Minimums: Pennsylvania’s $5,000 property damage limit leaves drivers vulnerable to out-of-pocket lawsuits following multi-car accidents.
- Failing to Update Policy Details: Changes in daily commute distance, marital status, or garaging address should be reflected on your policy to avoid underwriting disputes during a claim.
- Overlooking Policy Exclusions: Failing to read the fine print regarding business use of a personal vehicle (such as ridesharing or food delivery) can lead to denied claims.
Pitfalls When Reviewing Car Insurance Quotes in Bristol PA
When you review estimates, pay close attention to structural coverage details that some cut-rate policies omit. A common pitfall in Bristol is rejecting Uninsured and Underinsured Motorist (UM/UIM) coverage. With approximately 15% of local motorists driving uninsured, waiving UM/UIM protection leaves you vulnerable if an uninsured driver hits you.
Another mistake is miscalculating deductibles. Selecting a $1,500 deductible to save a few dollars a month can create severe financial strain if you cannot pay that amount out of pocket when your car needs collision repairs. Similarly, providing inaccurate annual mileage estimates can cause premium recalculations mid-term. When you want fast, dependable pricing without hidden traps, obtaining auto insurance quotes based on accurate, matched limits ensures you avoid these common pitfalls.
Frequently Asked Questions About Bristol Auto Coverage
How much does car insurance typically cost in Bristol, PA?
The average cost of car insurance in Bristol, PA is approximately $1,200 per year for full coverage. However, your actual rate will vary based on your age, driving history, credit tier, exact vehicle type, and chosen liability limits.
What is Pennsylvania’s minimum legal auto insurance requirement?
Pennsylvania law requires drivers to carry at least $15,000 of bodily injury liability per person, $30,000 of bodily injury liability per accident, $5,000 of property damage liability, and $5,000 in first-party medical benefits. Drivers must also select either a Limited Tort or Full Tort coverage option.
Why are car insurance rates in Bristol higher than the national average?
Rates in Bristol run roughly 10% higher than the national average due to elevated traffic density along the I-95 and Route 13 corridors, frequent winter weather hazards, local claim frequencies across Lower Bucks County, and an estimated 15% uninsured driver rate on regional roadways.
Conclusion
Securing the right auto coverage in Bristol, PA, is about striking a smart balance between dependable protection and manageable costs. While state minimums offer a tempting price point, they can leave you exposed to devastating personal liabilities after a major crash on Route 13 or I-95. By taking advantage of policy bundling, maintaining a clean driving record, selecting realistic deductibles, and preserving your rights with adequate liability limits, you can protect your financial well-being without overpaying.
At Newtown Insurance, we provide clear guidance, transparent pricing, and tailored policies for drivers throughout Bucks County. If you are ready to review your current policy and explore cost-effective options customized to your vehicle and budget, visit our services and coverage overview today.