Why Auto Insurance ID Cards Matter Before You Drive
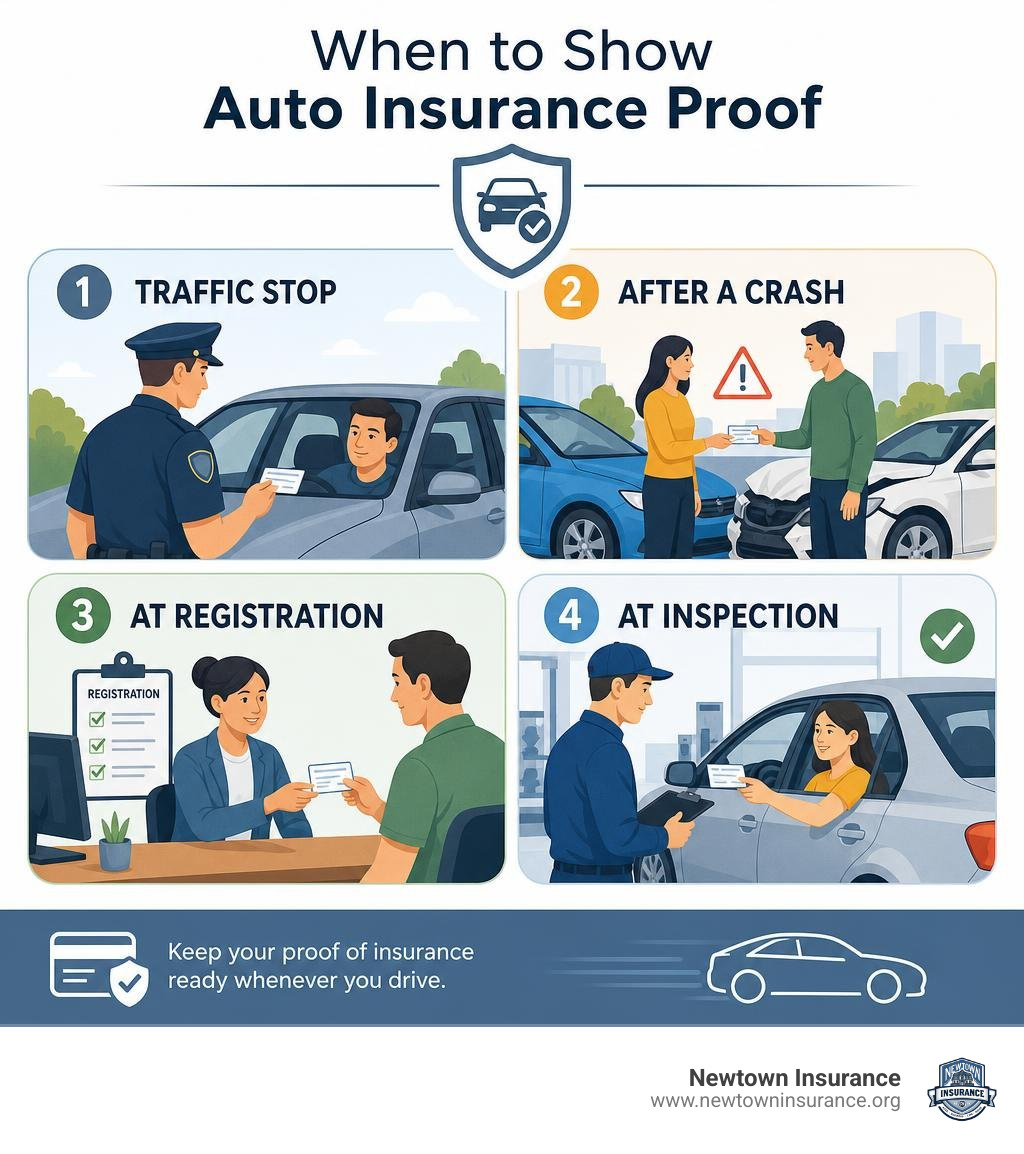
Auto insurance ID cards are your quick proof that a vehicle has active insurance. Keep a current card for every vehicle you drive, either as a paper copy or in your insurer’s mobile app where digital proof is accepted. You may need to show it during a traffic stop, after a crash, at registration or inspection, or when another party asks for coverage details.
Before driving, take these three steps:
- Check that the card lists the right vehicle, policy number, and effective dates.
- Save a digital copy and keep a paper backup in the vehicle.
- Replace the card right away after a renewal, vehicle change, or correction to your policy.
An ID card is not the insurance policy itself. It is evidence of coverage, and state rules can differ. For example, Pennsylvania uses state-specific proof-of-insurance requirements, while New York requires specially issued insurance cards rather than the standard ACORD 50 form. A card can also become invalid if the underlying policy has lapsed, even when its printed dates have not yet passed.
I am Shawn Beihl of Newtown Insurance, with more than 15 years of experience helping individuals and businesses understand coverage, documentation, and risk. In the sections ahead, I will break down Auto insurance ID cards, what must appear on them, and how to avoid preventable proof-of-insurance problems.
Basic Auto insurance ID cards terms:
Understanding What an Auto Insurance Identification Card Is
An auto insurance identification card serves as portable, verifiable proof of financial responsibility. Whenever you operate a motor vehicle on public roads, you are legally required to demonstrate that you carry the minimum liability protection mandated by state law. Whether you are managing personal driving needs or securing personal vehicle insurance, having an accurate, unexpired card in your vehicle protects you from immediate legal penalties during unexpected encounters.
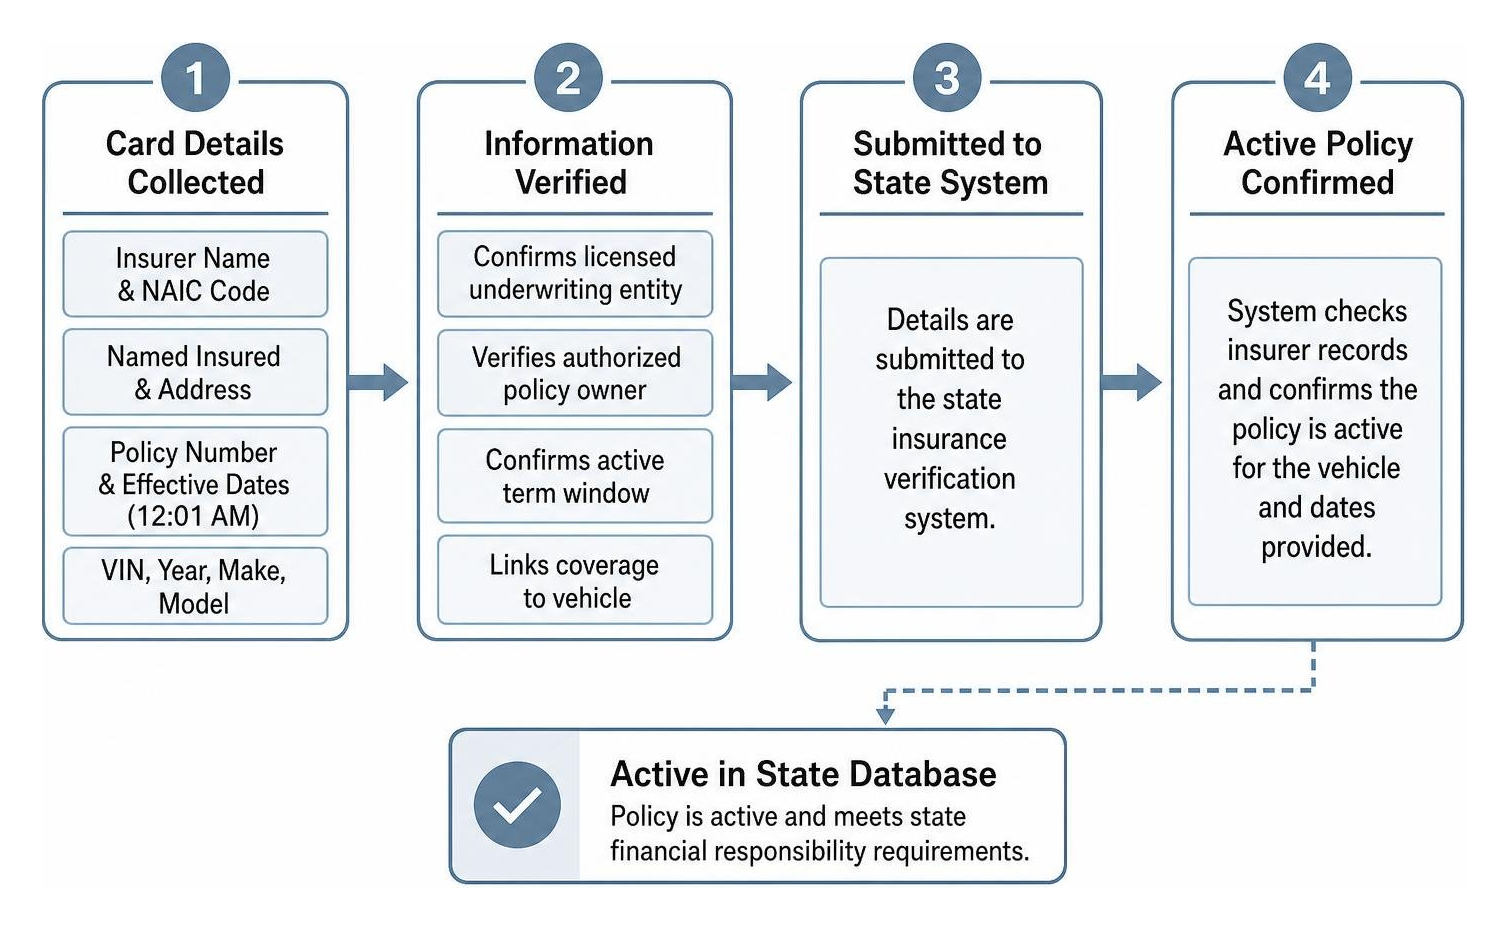
Your insurance card consolidates complex policy declarations into a concise, standardized format that law enforcement officers, department of motor vehicle (DMV) clerks, and accident investigators can instantly verify. It confirms your insurer’s legal identity, their National Association of Insurance Commissioners (NAIC) company code, your active policy number, and the exact window of effective dates.
You are generally required to produce your auto insurance ID card under several mandatory circumstances:
- Traffic stops: When pulled over by local or state law enforcement for any moving violation or routine check.
- Accident scenes: When exchanging information with other motorists, property owners, or responding police officers following a collision.
- Vehicle registration and title transfers: When registering a newly purchased car or renewing your existing license plates at the DMV or through an authorized issuing agent.
- Annual vehicle safety inspections: When taking your vehicle to an official state inspection mechanic to verify ongoing roadworthiness and legal compliance.
State Mandates and Minimum Coverage Requirements
Every state establishes strict financial responsibility laws to ensure motorists can cover the costs of bodily injury and property damage resulting from preventable accidents. When an insurance company issues an ID card, it certifies to state authorities that the underlying policy satisfies or exceeds these statutory baseline limits. Understanding state-specific auto insurance requirements ensures your documentation remains fully compliant during routine audits or licensing checks.
While basic liability principles apply across state lines, statutory minimums differ significantly:
- Pennsylvania: Drivers must maintain continuous financial responsibility meeting state liability requirements, verified by official agents following state insurance verification guidelines whenever handling title, registration, or tag renewals.
- Connecticut: Motorists must maintain minimum mandatory coverage of $25,000 per person and $50,000 per accident for bodily injury liability, $25,000 per accident for property damage liability, alongside matching $25,000/$50,000 uninsured and underinsured motorist protection limits.
- New York: Requires strict liability compliance along with mandatory personal injury protection (No-Fault) and uninsured motorist coverage, tracked directly through real-time state database links.
Commercial, Fleet, and Leased Vehicle Requirements
Documentation rules adapt when managing vehicles that fall outside single-owner personal policies. For leased vehicles, titling agencies and financial institutions require specific naming conventions. The identification card must clearly identify the lessee (the person driving and insuring the car) alongside the leasing institution (the legal lessor and titleholder). In most routine DMV interactions, an ID card listing only the lessee’s name is legally sufficient as long as the vehicle description and Vehicle Identification Number (VIN) match registration records precisely.
Commercial policies and business fleets operate under tailored identification guidelines:
- Fleet policies (5+ vehicles): For businesses managing five or more commercial motor vehicles, state insurance guidelines permit cards to display the phrase “all owned vehicles” rather than creating individual cards for every vehicle identification number.
- ACORD 50 form limitations: The standard commercial insurance industry proof form, the ACORD 50 Insurance Identification Card, is accepted across many jurisdictions. However, drivers and fleet managers must review ACORD 50 form standards and state exceptions, as 17 to 18 states do not accept this generic form for vehicle registration or road compliance—including Pennsylvania, New York, New Jersey, California, Texas, Florida, and Georgia.
Key Information Displayed on Auto Insurance ID Cards
A valid insurance card contains dense, standardized information designed for rapid legal verification. When evaluating comprehensive auto insurance, double-checking the accuracy of every printed field ensures seamless interactions with issuing agents and law enforcement.
Essential fields required on every standard auto insurance card include:
- Insurer legal name and NAIC code: The underwriting company’s formal corporate entity and its unique five-digit National Association of Insurance Commissioners identifier.
- Named insured details: The primary policyholder’s full legal name and mailing address.
- Policy number: The complete active policy account number, including any relevant prefix or suffix.
- Effective and expiration timestamps: Standardized coverage terms running explicitly from 12:01 a.m. on the starting date through 12:01 a.m. on the expiration date.
- Vehicle description: The precise model year, manufacturer make, model name, and full 17-digit VIN.
- Consumer disclosures: Specific statutory notices, such as state-mandated disclosures in bold capital letters reminding motorists of their legal right to choose any licensed auto body repair facility for claims repairs.
| Field / Requirement | Standard Personal Auto Card | Commercial / Fleet ID Card | Special Designation Vehicle Card |
|---|---|---|---|
| Vehicle Identification | Specific 17-digit VIN, Year, Make, Model | Specific VIN or “All Owned Vehicles” (5+ cars) | Specific VIN matching historical or work status |
| Named Insured | Individual policyholder(s) | Corporate entity or DBA | Registered individual or business entity |
| State Form Format | Standard state-specific card | State card or ACORD 50 (state-dependent) | Encrypted DMV form / statutory stamp |
| Mandatory Markings | Standard liability compliance | Commercial lines designation | “HISTORICAL”, “TOW TRUCK”, “REPLACEMENT” |
| Term Duration | 6 or 12 months (12:01 AM start/end) | Annual commercial term | Standard policy term or 30–45 day binder |
Understanding State Rules for Auto Insurance ID Cards
Because motor vehicle licensing is administered at the state level, format requirements and validation technologies differ markedly between jurisdictions:
- New York: Auto ID cards must be produced using proprietary, encrypted 2D barcode software provided directly by authorized insurance carriers (utilizing official forms such as the FS-20, FS-83, or temporary FS-21). These encrypted barcodes allow law enforcement and the NY DMV to instantly verify policy validity against real-time central databases.
- Connecticut: Insurance carriers operating under state motor vehicle statutes adhere to strict format mandates outlined in the Connecticut insurance card bulletin guidelines, including mandatory 12:01 a.m. policy timestamps, clear lessor/lessee designations, and bold repair shop choice notifications.
- Pennsylvania: Insurance issuing agents and law enforcement must verify physical or digital cards containing the insurer’s registered NAIC number, active policy dates, and exact VIN matching state Department of Transportation records, rejecting unauthorized generic templates.
Special Vehicle Markings and Designations
Specialty vehicle classes require clear visual indicators on the identification card to confirm specialized underwriting and regulatory compliance:
- Replacement vehicles: When purchasing a new car to replace an existing scheduled vehicle, insurers may issue temporary cards or binders marked “REPLACEMENT VEHICLE,” valid for an interim window (often 30 to 45 days) while permanent registration paperwork processes.
- Historical and antique vehicles: Classic cars registered under antique or historical designations must feature “HISTORICAL” on the card to reflect specialized limited-use underwriting when structuring personal auto insurance.
- Tow trucks and commercial haulers: Because municipal towing and recovery operations carry elevated liability risks, state regulations frequently mandate explicit “TOW TRUCK” markings across the face of the insurance card.
- Seasonal motorcycle lay-up: Policyholders utilizing winter lay-up endorsements suspend collision and road liability during non-riding months, but must ensure their identification documents accurately reflect seasonal status without accidentally triggering DMV lapse penalties.
Digital and Electronic Proof of Insurance Rules
Every modern driver benefits from the widespread legal recognition of digital auto insurance ID cards. State legislatures across the nation have updated motor vehicle codes to ensure electronic insurance cards presented on smartphones, tablets, and digital wallets carry the exact same legal weight as traditional physical paper cards.
Drivers can store and present their electronic proof of insurance in several ways:
- Official mobile insurer apps: Accessing an offline-capable digital card directly within your carrier’s smartphone application.
- Mobile wallet passes: Saving verified policy cards into Apple Wallet or Google Wallet for immediate one-tap roadside access.
- Downloaded PDF files: Storing an encrypted digital document in your phone’s offline file directory.
While digital proof offers unmatched convenience, carrying a physical paper backup in your glove compartment remains an essential best practice. Dead smartphone batteries, cracked screens, or poor cellular reception in rural areas can prevent you from displaying a digital card during an inspection or accident. Furthermore, state laws stipulate that while insurers can offer electronic delivery, they cannot force digital-only cards upon policyholders without affirmative consent and must provide physical paper copies upon request.
Law Enforcement Stops and Mobile Privacy Protections
A common concern among drivers is whether handing an unlocked smartphone to a police officer to show a digital insurance card exposes private text messages, photos, or browser history to search.
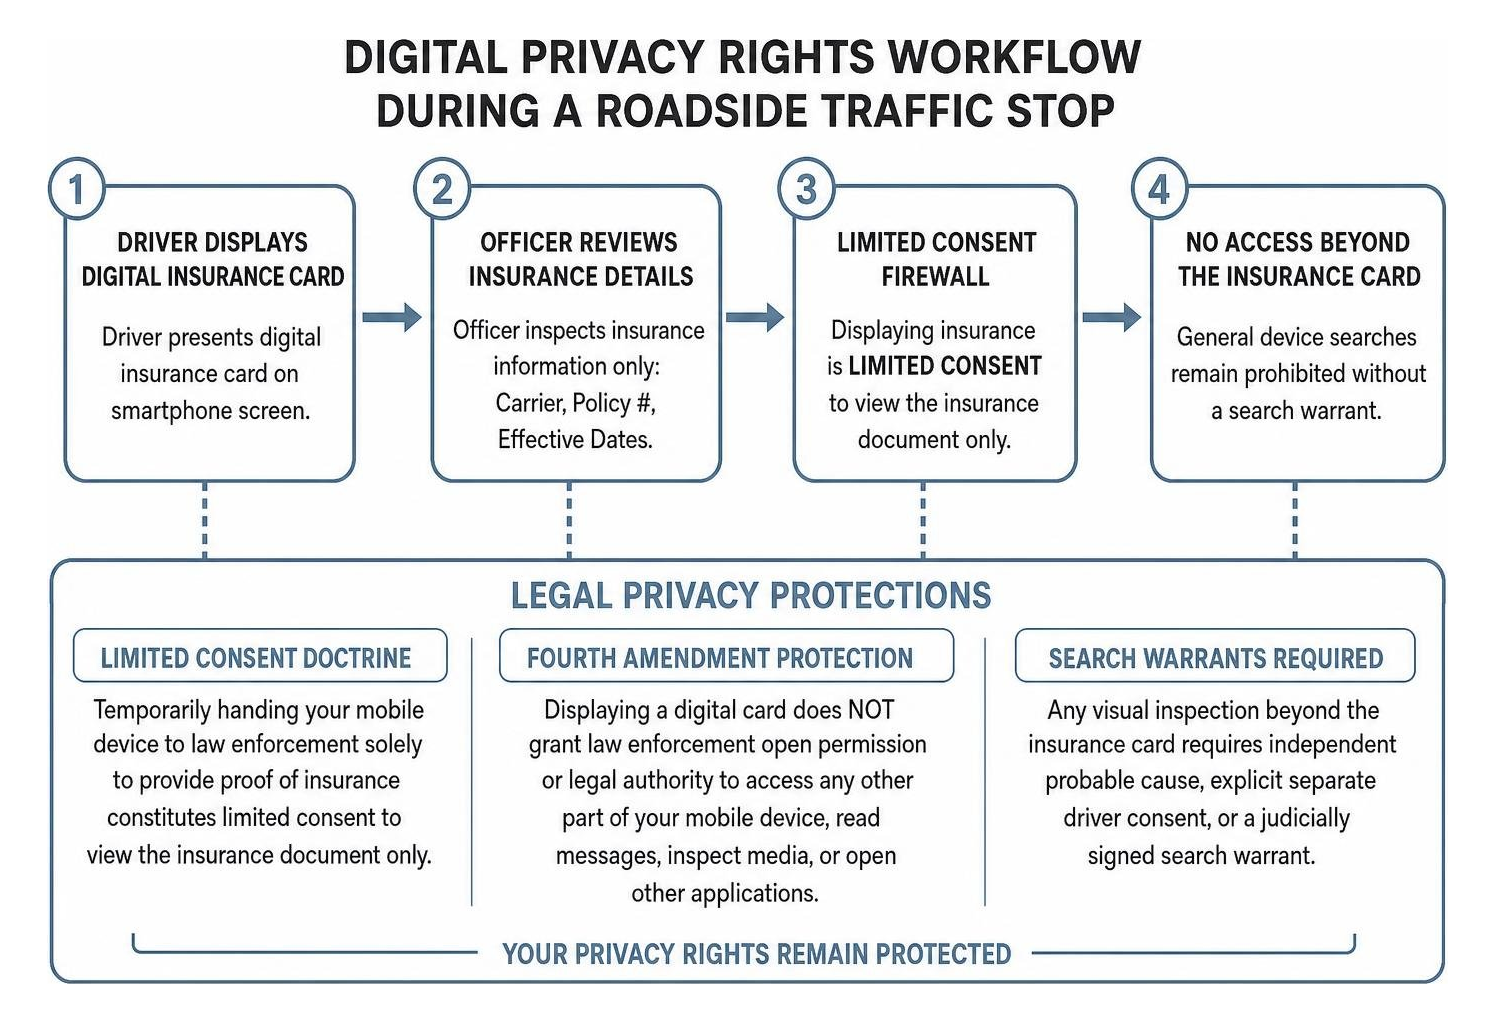
Statutory privacy protections establish that:
- Limited consent doctrine: Temporarily handing your mobile device to law enforcement personnel solely to provide proof of insurance constitutes limited consent to view the insurance document only.
- Fourth amendment protection: Displaying a digital card does not grant law enforcement open permission or legal authority to access any other part of your mobile device, read messages, inspect media, or open other applications.
- Search warrants required: Any visual inspection beyond the insurance card requires independent probable cause, explicit separate driver consent, or a judicially signed search warrant.
To maximize privacy during roadside interactions, use “guided access” on iOS or “app pinning” on Android to lock your screen exclusively to the insurance card before passing your phone to an officer.
Replacing Lost or Expired Auto Insurance ID Cards
If you misplace your glovebox card or your current card passes its expiration date, replacing it is fast and straightforward:
- Customer self-service portals: Log into your insurance customer portal from any desktop or mobile browser to immediately generate, download, or print a fresh PDF replacement.
- Automated renewal delivery: Insurers automatically issue updated physical and digital ID cards several weeks prior to the expiration of your 6-month or 12-month policy term.
- Instant temporary binders: If you change vehicles or alter coverage, our team can instantly email temporary proof of insurance documents to bridge the gap until permanent cards arrive.
- Exploring competitive options: If your upcoming renewal includes unexpected premium increases, you can quickly explore customized auto insurance quotes to secure better rates without risking a lapse in documentation.
Consequences and Penalties for Driving Without Proof of Coverage
Operating a motor vehicle without valid, active proof of insurance carries severe legal and financial consequences. Even if you maintain active coverage in your insurer’s database, failing to physically or digitally produce your ID card upon lawful demand is treated as a distinct legal violation in most jurisdictions.
Consequences of driving without verifiable insurance include:
- Immediate traffic citations: Law enforcement officers may issue civil citations for failure to produce proof of insurance, resulting in initial fines that often range from $100 to over $500 depending on the jurisdiction.
- Vehicle impoundment: In many municipalities, police officers are legally authorized to immediately tow and impound vehicles whose drivers cannot verify valid insurance during a stop.
- Driver’s license and registration suspensions: State DMVs routinely suspend vehicle registrations and driving privileges for unverified insurance, requiring formal restoration fees, administrative surcharges, and mandatory SR-22/financial responsibility filings before reinstating driving rights.
- Court appearances and dismissals: If you held active insurance at the exact moment of the traffic stop but merely lacked the card, most municipal courts will dismiss or drastically reduce the citation upon post-incident proof submission, though administrative court processing fees may still apply.
Frequently Asked Questions About Auto Insurance Cards
Are electronic insurance ID cards accepted in all states?
Yes. Nearly every state and jurisdiction across the United States has enacted legislation permitting drivers to present electronic proof of insurance on portable electronic devices during traffic stops, vehicle safety inspections, and registration renewals. However, while law enforcement officers accept digital images on smartphones, certain behind-the-scenes titling or dealer transfer transactions may still require physical paper printouts.
Does showing my digital insurance card let police search my phone?
No. State and federal statutes establish that presenting an electronic insurance ID card grants law enforcement strictly limited consent to view the displayed insurance credential. It does not authorize officers to look through personal photos, text messages, phone logs, or other smartphone apps without obtaining an independent search warrant or receiving explicit, voluntary consent.
What should I do if my insurance card contains incorrect vehicle details?
If you notice an error in your name, address, policy effective dates, or any single digit of your 17-digit VIN, contact your insurance provider immediately. An incorrect VIN can cause a DMV registration rejection or trigger a false uninsured-vehicle notice. Your agent will issue an immediate policy endorsement and generate an updated, corrected ID card on the spot.
Conclusion
Your auto insurance ID card is your first line of defense against roadside citations, registration delays, and legal complications. By maintaining active coverage, storing a digital copy in your smartphone wallet, and keeping a physical paper backup tucked securely inside your vehicle’s glovebox, you ensure total preparedness wherever the road takes you.
At Newtown Insurance, our local team provides tailored protection, smart savings, and transparent pricing with dedicated, customer-first support to help you avoid overpaying for essential coverage. If you are reviewing your current policy, updating your vehicles, or looking to maximize your family’s auto coverage, contact us to explore complete protection tailored to your lifestyle.