Get Personal Health Insurance Quotes Before You Enroll
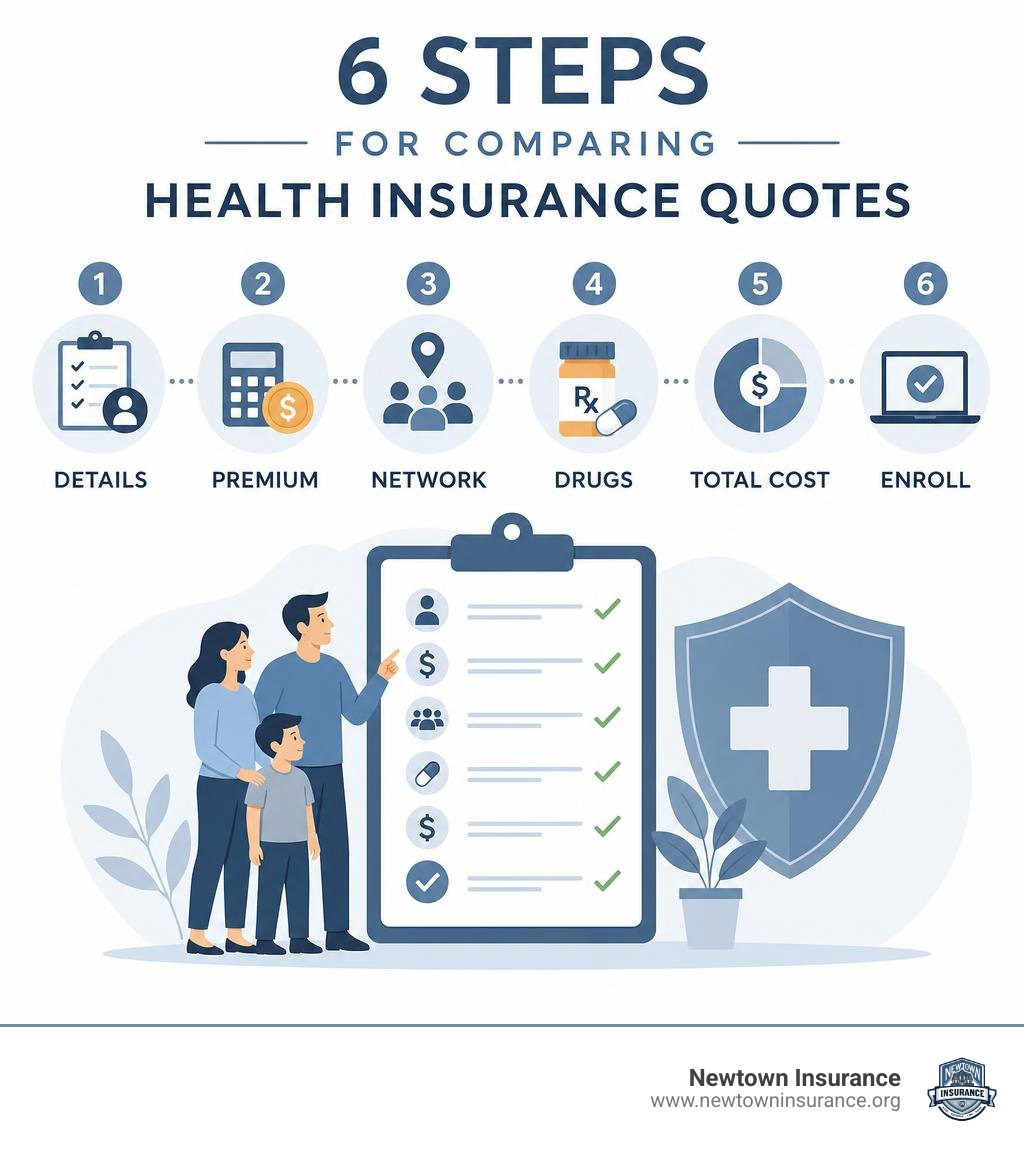
To find useful personal health insurance quotes, compare plans using the same details each time: your ZIP code, age, household size, estimated 2026 income, preferred doctors, and prescriptions. Then look beyond the monthly premium. Check the deductible, provider network, drug coverage, and the plan’s annual out-of-pocket limit before choosing.
In 2026, prices can vary sharply by location, age, and plan level. A benchmark Silver plan averages $625 per month nationally for a 40-year-old before financial help, but your final price may be far lower if you qualify for premium tax credits. Pennsylvania residents should also verify plans through the state’s Marketplace and confirm that local providers are in network.
The goal is not simply to find the lowest quote. It is to find coverage that fits both your monthly budget and the amount you could afford to pay when you need care.
I am Shawn Beihl of Newtown Insurance. With more than 15 years of experience in health, benefits, disability, and risk advising, I help people make sense of personal health insurance quotes and compare coverage without overlooking important costs.
Related content about personal health insurance quotes:
Understanding 2026 Coverage Costs and Metal Tiers
Getting an accurate picture of healthcare expenses in 2026 requires looking at the broader economic landscape. Across the country, health coverage costs have surged, with the national benchmark Silver plan rising roughly 26 percent year over year to reach $625 per month for an unsubsidized 40-year-old. This jump stems from ongoing medical inflation, broader utilization of specialty treatments, and soaring claims for GLP-1 medications.
To make sense of your options and find the right balance between routine expenses and catastrophic protection, our guide on Pennsylvania Health Insurance 101 Finding the Right Plan for Your Budget breaks down how these market dynamics influence everyday rates.
Every Affordable Care Act (ACA) marketplace plan is organized into standardized “metal tiers.” These tiers indicate the actuarial value (AV) of the policy—meaning the average percentage of total healthcare costs the insurer covers across a standard population, leaving the remainder to you via deductibles, copays, and coinsurance.
Here is how baseline costs stack up across the four major metal tiers in 2026 for an unsubsidized 40-year-old non-smoker:
| Metal Tier | Average Monthly Premium | Actuarial Value (AV) | Average Individual Deductible | Primary Cost-Sharing Profile |
|---|---|---|---|---|
| Bronze | $476 | 60% | $7,500 | Lowest monthly cost; highest out-of-pocket expenses when accessing care |
| Silver | $625 | 70% | $5,000 | Moderate monthly cost; eligible for extra savings via Cost-Sharing Reductions |
| Gold | $659 | 80% | $1,500 | Higher monthly premium; predictable, lower copayments and deductibles |
| Platinum | $841 | 90% | $500 | Highest monthly premium; near-total cost absorption by the insurer |
Bronze, Silver, Gold, and Platinum Breakdown
When evaluating these tiers, actuarial value does not reflect the exact percentage of your individual hospital bill that gets paid. Rather, it represents the statistical split across all enrollees.
- Bronze Plans (60% AV): These policies come with the lowest monthly bills ($476/month average), but they feature substantial average deductibles near $7,500. They work well for individuals who rarely see a physician beyond annual wellness exams and need a safety net against severe illness or injury.
- Silver Plans (70% AV): Serving as the benchmark for federal calculations, Silver plans sit right in the middle at $625/month with an average $5,000 deductible. Crucially, Silver is the only tier where eligible lower-income policyholders can receive Cost-Sharing Reductions (CSRs), which artificially boost the plan’s actuarial value up to 87% or 94%. State residents can explore baseline consumer protections and standards directly through the Health Insurance | Insurance Department portal.
- Gold Plans (80% AV): At $659/month, Gold plans carry an average deductible of just $1,500. Because the premium gap between Silver and Gold has narrowed in many areas, Gold often presents exceptional value for people who manage ongoing prescriptions or visit specialists regularly.
- Platinum Plans (90% AV): With premiums averaging $841/month, Platinum plans feature rock-bottom deductibles around $500 and minimal copays. They provide maximum budget predictability for individuals facing major planned surgeries, chronic conditions, or frequent hospitalizations.
Evaluating Plan Tiers Before Requesting Personal Health Insurance Quotes
Before pulling numbers, think through how your household actually uses healthcare. If you qualify for an income-based subsidy and earn between 100% and 250% of the Federal Poverty Level (FPL), a Silver plan is almost always the smartest mathematical choice because CSRs lower your out-of-pocket deductibles dramatically without raising your monthly rate.
On the other hand, if you are healthy, earn too much for cost-sharing subsidies, and want to reduce taxable income, a Bronze High-Deductible Health Plan (HDHP) paired with a Health Savings Account (HSA) allows you to set aside pre-tax dollars for medical expenses while keeping monthly premiums low.
The 2026 ACA Subsidy Cliff and Eligibility Rules
The major shift defining 2026 coverage is the return of the ACA “subsidy cliff.” Temporary subsidy expansions introduced under the American Rescue Plan Act and extended by the Inflation Act expired on December 31, 2025.
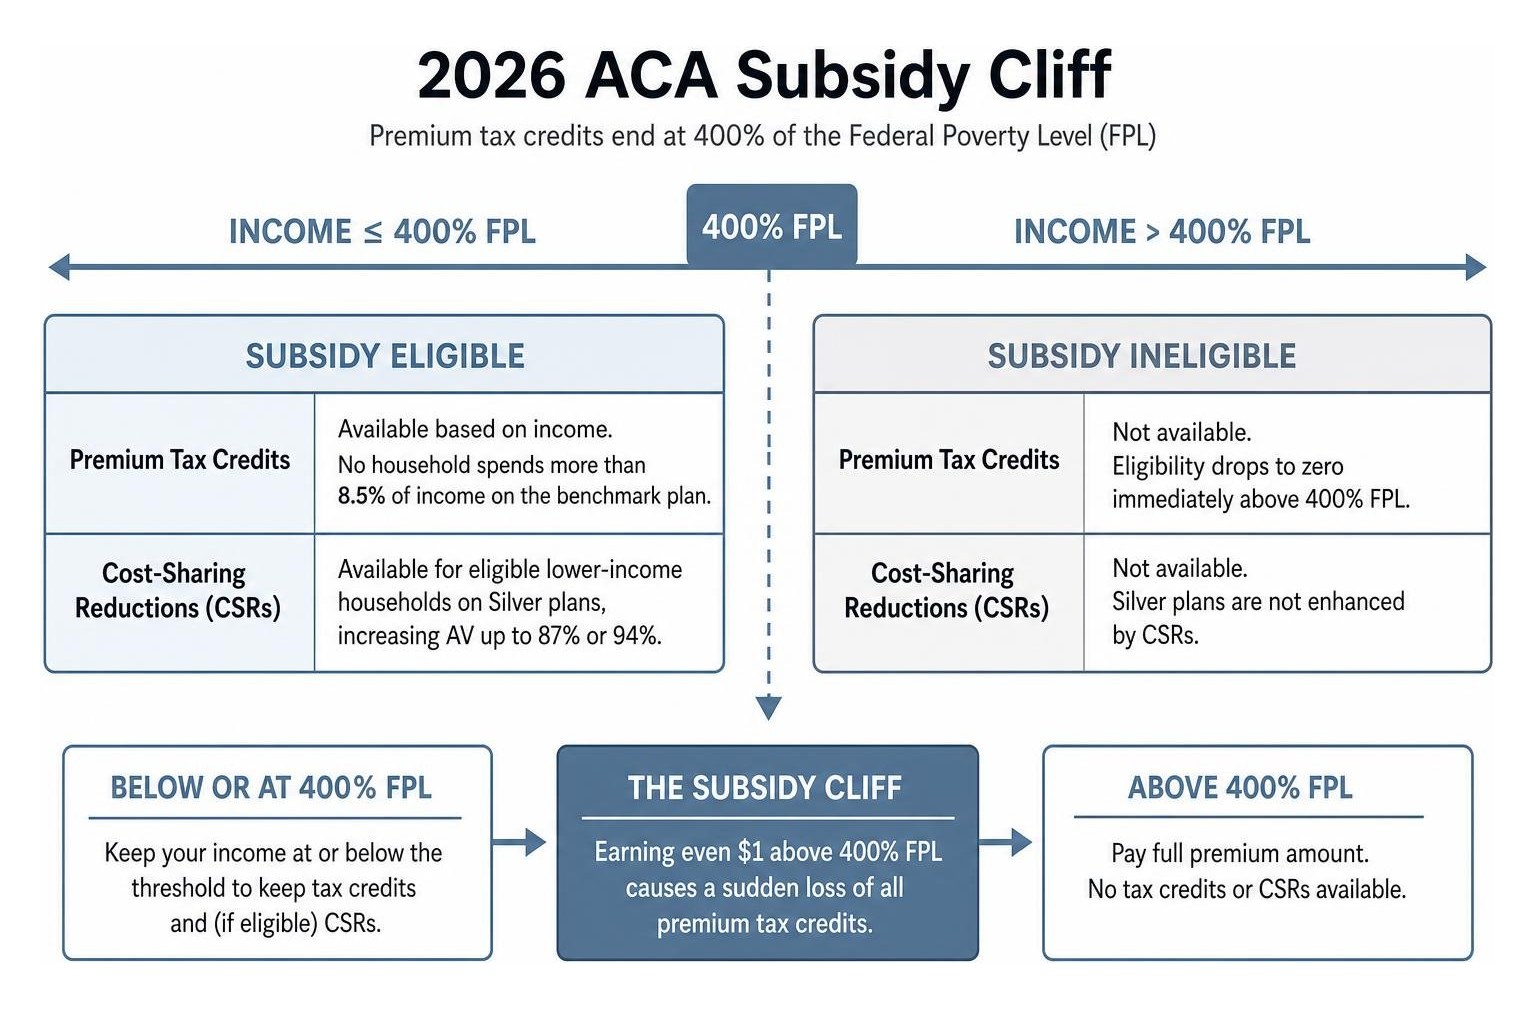
Prior to 2026, premium tax credits were capped so that no household spent more than 8.5% of their income on a benchmark plan, regardless of total earnings. Now, the statutory cap at 400% of the FPL is back in full force. If your household modified adjusted gross income (MAGI) climbs even $1 above 400% FPL, your eligibility for premium tax credits immediately drops to zero.
To better understand how these legislative changes affect local families, take a look at our breakdown on Navigating the 2026 PA Health Insurance Rate Rollercoaster. For broader historical context, you can review this Health Insurance 2026: $625/mo Benchmark, Cliff Back at 400% FPL analysis.
Income Thresholds and Household Size Calculations
Because premium tax credits depend strictly on where your income lands relative to the poverty guidelines, knowing your 2026 FPL boundaries is essential:
- Single Individual (100% to 400% FPL): $15,650 to $62,600
- Two-Person Household: $21,150 to $84,600
- Family of Four: $32,150 to $128,600
If a single filer earns $62,500, they remain under the 400% FPL threshold and receive financial assistance to keep their benchmark plan affordable. If their income edges up to $62,700, they lose all assistance and must pay 100% of the market rate.
Estimating Personal Health Insurance Quotes by Income and Household Size
The real-world consequence of the cliff is especially visible for older adults due to the ACA’s 3:1 age rating curve, which allows carriers to charge 64-year-olds up to three times what they charge 21-year-olds ($1,467/month vs. $489/month for unsubsidized benchmark coverage).
Consider a 60-year-old living in an area where standard benchmark coverage costs $1,450 per month:
- Income at $62,500 (Under 400% FPL): Receives an estimated tax credit of $940/month, resulting in a net monthly premium of roughly $510.
- Income at $63,000 (Over 400% FPL): Loses the entire tax credit and pays the full $1,450 per month—a net difference of over $11,000 annually for earning just $500 more.
For a 40-year-old earning around standard median levels, an estimated monthly benchmark premium might be $847 before a $390 tax credit reduces the net payment to $457. Calculating your MAGI precisely—accounting for traditional 401(k) contributions, IRA deposits, and HSA contributions—can keep you safely below the 400% threshold.
How to Accurately Compare Personal Health Insurance Quotes
When browsing through plans, looking exclusively at the monthly premium is the easiest way to make an expensive mistake. A comprehensive review requires evaluating several core components together:
- Provider Networks: Check whether your preferred physicians and local hospitals are in-network. Health Maintenance Organization (HMO) and Exclusive Provider Organization (EPO) plans rarely cover non-emergency out-of-network care, while Preferred Provider Organization (PPO) plans offer out-of-network flexibility at higher coinsurance rates.
- Prescription Drug Formularies: Review the plan’s tiered formulary to see how your medications are classified (Tier 1 generic vs. Tier 3/4 specialty) and whether prior authorization is required.
- Out-of-Pocket Maximum: This is the legal ceiling on what you will pay in a single calendar year for covered in-network essential health benefits. For 2026, the maximum out-of-pocket limit is capped at $10,600 for individuals and $21,200 for families.
For a wider framework on evaluating different plan structures, check out our Compare Insurance Quotes Complete Guide.
Marketplace vs. Employer-Sponsored Insurance
Employer-sponsored coverage remains the most common way Americans get insured, and it is usually the most cost-effective. On average, employers cover approximately 84% of individual premiums and 75% of family plans:
- Individual Employer Coverage: The employee share averages roughly $120 per month.
- Marketplace Individual Coverage: Benchmark Silver averages $625 per month before any tax credits.
- Family of Four Marketplace Coverage: A benchmark Silver plan averages approximately $1,998 per month unsubsidized, compared to an average employee contribution of around $571 per month under employer-sponsored plans.
If your employer offers coverage deemed “affordable” under ACA guidelines (meaning the employee-only premium does not exceed a set percentage of household income), you generally cannot claim Marketplace tax credits. However, if your employer plan fails the affordability test, you can decline it and seek subsidized individual coverage.
Anonymity and Quote Gathering Best Practices
Shopping for health coverage can quickly lead to unwanted sales calls if you provide contact details to lead-generation forms. Fortunately, you can research plan designs, metal tiers, and baseline prices without giving away your personal details.
Learn how to safeguard your inbox using our guide on Can You Get Health Insurance Quote Without Giving Personal Information. Once you are ready to apply and finalize your plan, working through our trusted process for Personalized Insurance Quotes guarantees that your information stays secure while we match you with the right policy.
Step-by-Step Guide to Enrolling in Coverage
Navigating the individual marketplace does not have to be stressful. Following a clear, sequential path ensures you secure comprehensive coverage without missing critical enrollment windows.
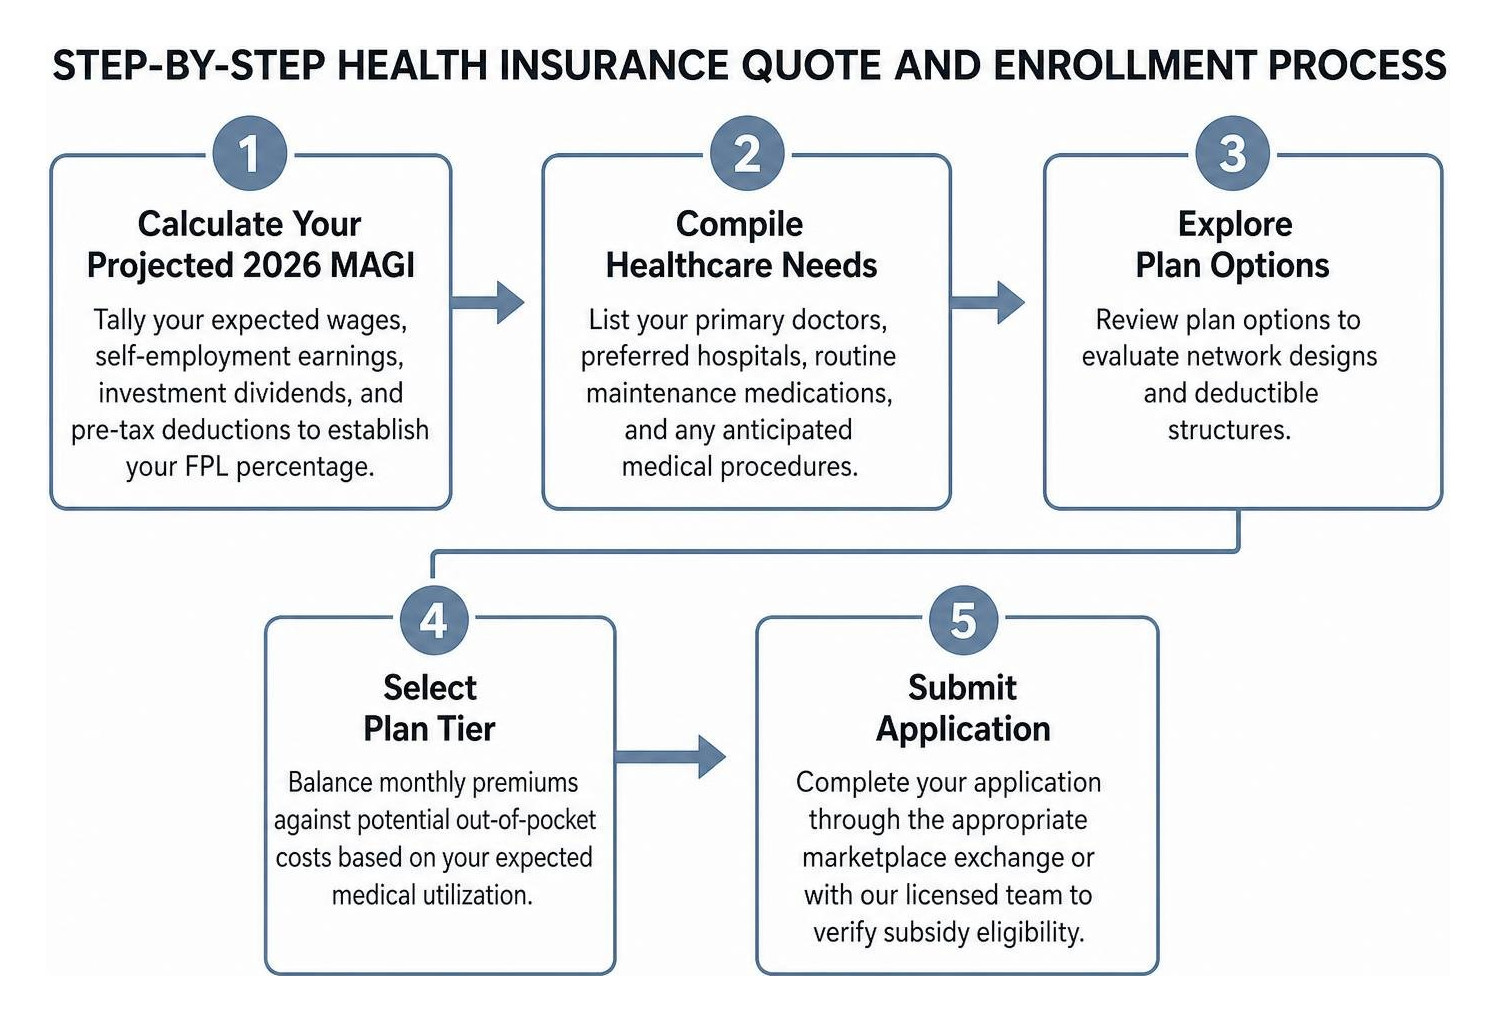
- Calculate Your Projected 2026 MAGI: Tally your expected wages, self-employment earnings, investment dividends, and pre-tax deductions to establish your FPL percentage.
- Compile Healthcare Needs: List your primary doctors, preferred hospitals, routine maintenance medications, and any anticipated medical procedures.
- Explore Plan Options: Review our detailed Health Insurance Quotes Guide 2026 to evaluate network designs and deductible structures.
- Select Plan Tier: Balance monthly premiums against potential out-of-pocket costs based on your expected medical utilization.
- Submit Application: Complete your application through the appropriate marketplace exchange or with our licensed team to verify subsidy eligibility.
- Pay Initial Premium: Remit your first monthly payment before the coverage effective date to fully activate your policy.
Key Enrollment Windows and Deadlines
Open Enrollment for individual coverage begins on November 1 and runs through December 15 for coverage taking effect on January 1. Under federal marketplace integrity rules, missing the December 15 deadline restricts your ability to enroll unless you qualify for a Special Enrollment Period (SEP).
SEPs last 60 days following a Qualifying Life Event (QLE), which includes:
- Loss of qualifying minimum essential coverage (such as leaving a job or aging off a parent’s plan at 26)
- Marriage, divorce, or legal separation resulting in loss of insurance
- Birth, adoption, or foster care placement of a child
- Permanent relocation to a new rating area with different plan availability
Low-Cost Alternatives: Medicaid, Catastrophic, and HDHPs
If standard Marketplace plans stretch your finances, several low-cost paths are available:
- Medicaid: In states that have expanded Medicaid, individuals and families earning up to 138% of the FPL ($21,597 for a single person in 2026) qualify for free or very low-cost coverage with zero deductibles and minimal copays. Medicaid enrollment remains open year-round.
- Catastrophic Plans: Available to adults under age 30 or individuals with an approved hardship or affordability exemption. These plans offer low monthly premiums and cover essential preventive care at no initial cost, but carry the maximum allowable legal deductible ($10,600 in 2026).
- HDHPs with HSAs: High-deductible health plans allow eligible individuals to make triple-tax-advantaged contributions into a Health Savings Account (tax-deductible deposits, tax-free growth, and tax-free withdrawals for qualified medical expenses).
Frequently Asked Questions About Individual Health Insurance
How much does personal health insurance cost per month in 2026?
For an unsubsidized 40-year-old, average monthly premiums across metal tiers are:
- Bronze: $476
- Silver (National Benchmark): $625
- Gold: $659
- Platinum: $841
Actual rates depend heavily on age, location, and subsidy eligibility. A 21-year-old pays roughly $489 per month for a benchmark plan, whereas a 64-year-old pays approximately $1,467 before tax credits. Subsidies can reduce net monthly costs significantly for households earning under 400% FPL.
What is the out-of-pocket maximum for 2026 and what does it cover?
The 2026 out-of-pocket maximum is capped at $10,600 for individual plans and $21,200 for family plans.
This maximum covers all cost-sharing requirements—including deductibles, copayments, and coinsurance—for in-network essential health benefits. Once you hit this threshold during the calendar year, the insurance company pays 100% of covered medical costs. It does not cover monthly premiums, out-of-network services, or non-covered elective treatments.
When is the next open enrollment period, and how can I enroll outside it?
Standard Open Enrollment begins November 1, 2026, and concludes on December 15, 2026, for coverage starting January 1, 2027.
To enroll outside this window, you must experience a Qualifying Life Event (such as losing job-based insurance, moving, getting married, or having a child) to trigger a 60-day Special Enrollment Period. Enrollees eligible for Medicaid or CHIP can apply at any point during the year without waiting for an enrollment window.
Conclusion
Finding the right individual health plan comes down to matching your budget, lifestyle, and medical needs against changing market rules. With 2026 benchmark Silver rates averaging $625 per month and the ACA subsidy cliff back at 400% FPL, careful planning is more important than ever.
Take time to review total costs—not just monthly premiums, but deductibles, prescription formularies, and the $10,600 individual out-of-pocket maximum. If you need local guidance navigating your options, our team at Newtown Insurance is here to help you review plans, claim every dollar of financial assistance you qualify for, and secure reliable coverage for the year ahead. Explore our comprehensive services and connect with an advisor by visiting our Services Content page today.