
Finding the Right Insurance Company in Lancaster, PA
To find insurance companies in Lancaster, PA, start with the Pennsylvania Insurance Department’s company search. Then ask a local independent agency to compare quotes from multiple insurers. Keep coverage limits and deductibles the same across quotes so you can spot real price differences. Ask about bundle discounts and how each insurer handles claims, too.
Lancaster County’s insurance market is shaped by its mix of historic neighborhoods, working farms, and growing suburban corridors. That means the right carrier for a downtown Lancaster rowhouse may not be the best fit for a rural property with outbuildings or a small business fleet. Working with a local independent agent helps you match your specific risk profile to the carrier that prices it most fairly.
I’m Shawn Beihl. I’ve spent over 15 years helping people weigh coverage from insurance companies in Lancaster PA and beyond, with experience in life, health, and commercial insurance.
Insurance companies in lancaster pa terms to learn:
Overview of Insurance Companies in Lancaster PA
Lancaster County features a vibrant and competitive insurance market. Currently, over 30 licensed insurance carriers serve the county, ranging from household national brands to historic regional mutual firms that have operated across the Susquehanna Valley for generations. This broad selection gives local residents and business owners substantial leverage when shopping for coverage, provided they understand how carriers evaluate risk.
When exploring the top Pennsylvania auto options, customer satisfaction hinges primarily on two factors: transparent pricing and reliable claims handling. National carriers often provide robust digital platforms, mobile claims tools, and round-the-clock policy management. On the other hand, regional mutual insurers often emphasize localized underwriting and personalized, high-touch customer support.
A major advantage for Lancaster County policyholders is that regional premiums consistently trend lower than state and national benchmarks:
| Coverage Type | Lancaster County Average | Pennsylvania State Average | National Average |
|---|---|---|---|
| Auto Insurance (Annual) | $1,450 | $1,580 | $1,650 |
| Homeowners Insurance (Annual) | $1,200 | $1,310 | $1,428 |
| Property Crime Rate (per 1k) | 15.2 | 17.8 | 21.7 |
While overall average premiums in Lancaster rose roughly 4.2% over the past year due to broader repair inflation and severe weather claims, the region remains an affordable market relative to neighboring metropolitan areas. Policyholders who review their coverage annually and compare quotes from several carriers are best positioned to keep those costs in check.
Local Factors Driving Premium Costs in Lancaster County
Insurance premiums reflect localized risk metrics. In Lancaster County, several distinct geographic and demographic elements influence what you pay for coverage.

The property crime rate in Lancaster County sits at approximately 15.2 per 1,000 residents, which is 30% below the national average. Lower rates of burglary, theft, and property vandalism directly decrease the risk exposure for homeowners carriers, translating to lower baseline dwelling and personal property rates.
Vehicle coverage costs follow a similar trend. Analyzing the car insurance rates in Pennsylvania shows that Lancaster drivers benefit from lower traffic density than Philadelphia or Pittsburgh commuters. However, unique local driving conditions exist. Lancaster roadways feature a blend of suburban commercial corridors like Route 30 and rural secondary roads where agricultural equipment, buggies, and wildlife frequently share the lane.
Understanding the average cost of PA car insurance helps put Lancaster’s $1,450 baseline into context. While regional drivers enjoy an 8% savings compared to the statewide average, seasonal weather events like freeze-thaw cycles and severe summer hail can produce sudden spikes in comprehensive claims. Repair inflation has also pushed collision claim payouts higher, which is why many local drivers are revisiting their deductibles and coverage limits during annual policy reviews.
Comparing Essential Coverage Types and Policy Bundles
Working with an independent agency allows you to compare multiple carriers side by side while tailoring individual policy endorsements to your exact needs. An independent broker can assemble comprehensive packages that protect your home, vehicles, and liability under coordinated coverage limits.

Reviewing our full guide to Pennsylvania insurance highlights that bundling auto and home insurance remains the single most effective way to secure premium discounts, often reducing annual totals by 15% to 25%. Beyond the savings, bundling simplifies policy management by consolidating renewal dates, billing cycles, and claims contacts under one carrier.
Auto and Home Policies from Insurance Companies in Lancaster PA
Every driver in the Commonwealth must maintain minimum liability protection. Familiarizing yourself with state Pennsylvania auto insurance requirements ensures your policy complies with state law, which mandates:
- $15,000 bodily injury liability per person
- $30,000 bodily injury liability per accident
- $5,000 property damage liability
- $5,000 medical benefits coverage
Because medical care and vehicle repairs can easily exceed state minimums, many drivers consult the 2026 PA auto guide to evaluate higher liability limits alongside collision and comprehensive coverage. Raising liability limits is often surprisingly affordable and provides meaningful protection against out-of-pocket costs after a serious accident.
For residential properties, our Pennsylvania homeowners insurance guide outlines how dwelling replacement costs differ from market value. With Lancaster’s historic housing stock and custom farmhouses, selecting accurate replacement cost endorsements is vital to ensure complete rebuilding protection. Older homes may also benefit from ordinance or law coverage, which helps pay for upgrades required by current building codes during reconstruction.
Evaluating Health and Business Insurance Companies in Lancaster PA
Health coverage demographics in Lancaster present a distinct regional profile. Approximately 12% of Lancaster County residents are uninsured for health coverage, compared to the Pennsylvania statewide rate of 6.5%. This gap is largely driven by Lancaster’s concentration of self-employed tradespeople, agricultural operations, and small family enterprises.
For local business owners, securing dependable commercial liability, property, and group benefits is essential. If you operate an enterprise in the region, examining options for small business health coverage in PA can help you attract and retain quality staff while controlling overhead expenses. Comparing insurance companies across Pennsylvania gives business owners the flexibility to protect assets against premises liability, worker injuries, and commercial auto exposures. A well-structured commercial package can also include business interruption coverage, which replaces lost income if a covered event forces you to temporarily close your doors.
Smart Strategies to Maximize Savings and Verify Licensure
Policyholders can take practical steps to manage their premiums without sacrificing essential protection:
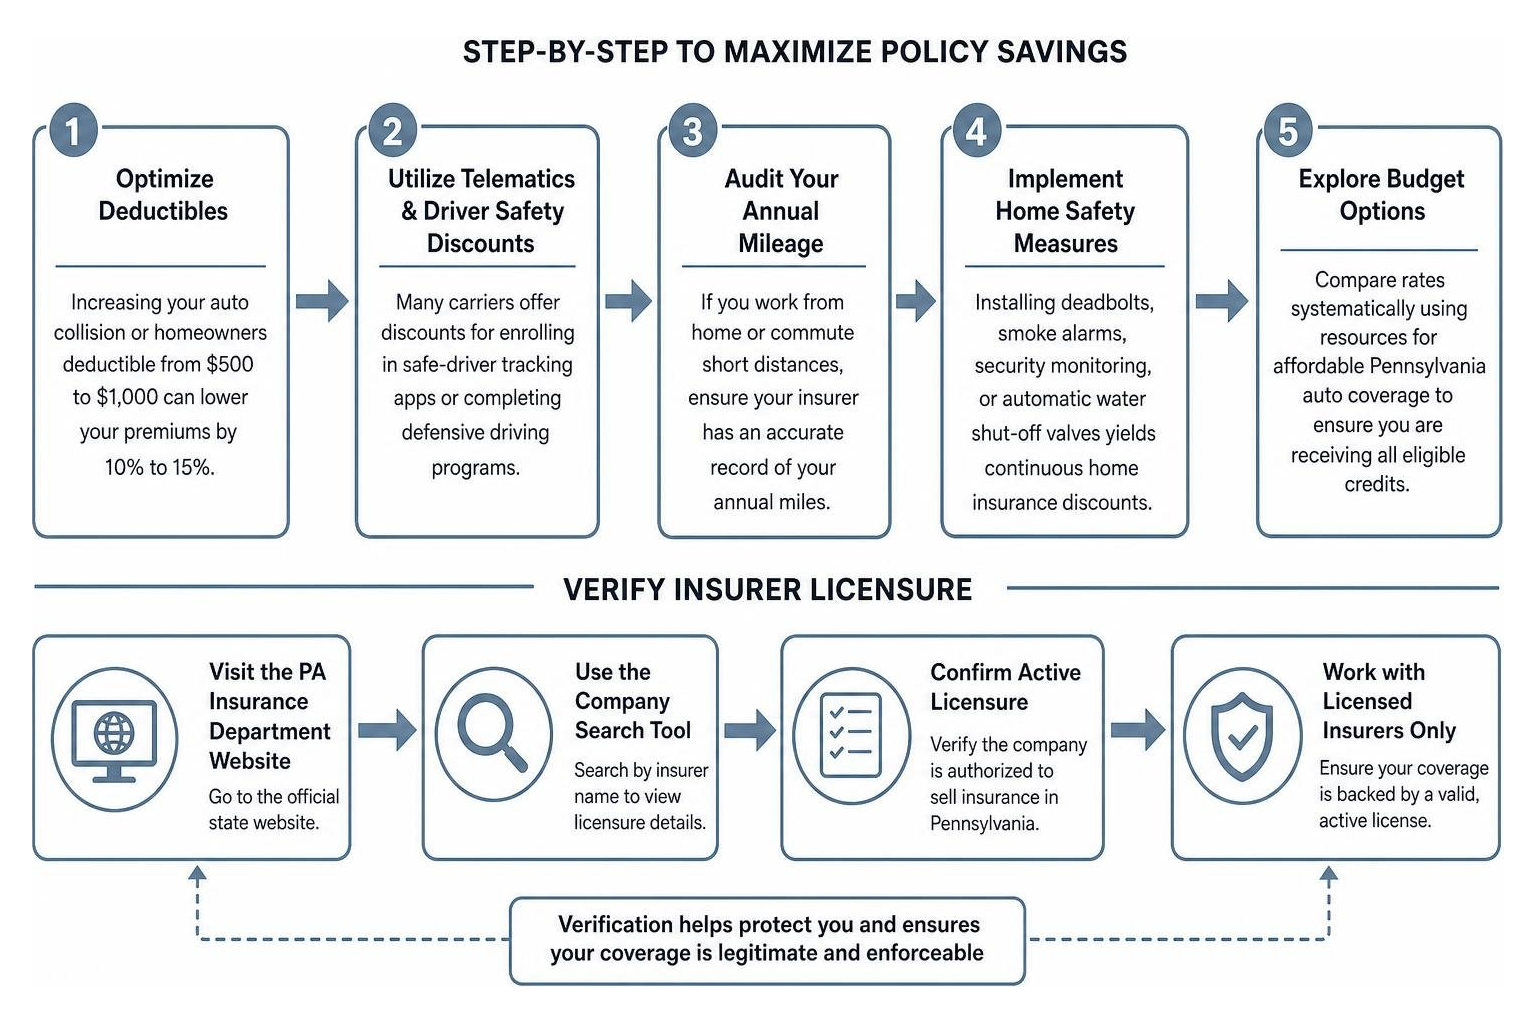
- Optimize Deductibles: Increasing your auto collision or homeowners deductible from $500 to $1,000 can lower your recurring premiums by 10% to 15%.
- Utilize Telematics and Driver Safety Discounts: Many regional and national carriers offer discounts for enrolling in safe-driver tracking apps or completing defensive driving programs.
- Audit Your Annual Mileage: If you work from home or commute short distances, make sure your insurer has an accurate record of your annual driving miles.
- Implement Home Safety Measures: Installing deadbolts, smoke alarms, security monitoring, or automatic water shut-off valves yields continuous home insurance discounts.
- Explore Budget Options: Compare rates systematically using resources for affordable Pennsylvania auto coverage to ensure you are receiving all eligible credits.
Before finalizing any policy, verify your agent’s licensing status. You can Find and Research an Insurance Agent or Company or look up regulatory standings via the state’s portal for Finding an Insurance Company to confirm that the carrier is fully authorized and in good standing with the Pennsylvania Insurance Department. Taking a few minutes to check licensure protects you from unlicensed operators and gives you a clear path for dispute resolution if a claim or billing issue ever arises.
Frequently Asked Questions About Lancaster County Insurance
How do average insurance rates in Lancaster compare to state averages?
Lancaster County residents generally pay lower premiums than the statewide average. Auto insurance runs approximately $1,450 annually (about 8% lower than the Pennsylvania average of $1,580), while homeowners insurance averages $1,200 per year, compared to the national average of $1,428. These favorable rates reflect lower local crime rates and reduced traffic congestion relative to major urban hubs.
What regulatory requirements apply to insurers operating in Lancaster?
All insurance carriers operating in Lancaster must be licensed and regulated by the Pennsylvania Insurance Department. Insurers must comply with Title 40 of the Pennsylvania Consolidated Statutes, participate in state guaranty funds, follow established bad-faith claim guidelines, and submit their premium rating schedules for regulatory review. Policyholders can confirm a carrier’s standing at any time through the department’s online company search tool.
How do local providers handle emergency disaster claims?
During severe weather events like heavy snowstorms, localized flooding, or straight-line wind damage, reputable carriers deploy rapid-response catastrophe teams. Most providers provide 24/7 digital and phone claim reporting, assign local field adjusters for rapid on-site inspections, and can issue immediate advance payments for temporary living expenses when homes sustain structural damage. Documenting damage with photos and keeping receipts for emergency repairs helps speed the process along.
Conclusion
Finding the right insurance balance requires comparing competitive rates, verifying strong financial backing, and choosing coverage that addresses your personal and commercial risks. An annual policy review ensures you aren’t paying for outdated coverage or missing newly introduced discounts. Life changes such as buying a home, adding a teen driver, or expanding a business can all shift your coverage needs, so a yearly check-in with a local agent is a smart habit.
At Newtown Insurance, our team delivers transparent pricing, tailored coverage, and dedicated local support. Let’s chat about your current policies to confirm you have the right protection at the right price. Connect with Shawn Beihl and our team to explore tailored Pennsylvania protection today.