
Finding Car Insurance in Hershey, PA, Without Overpaying
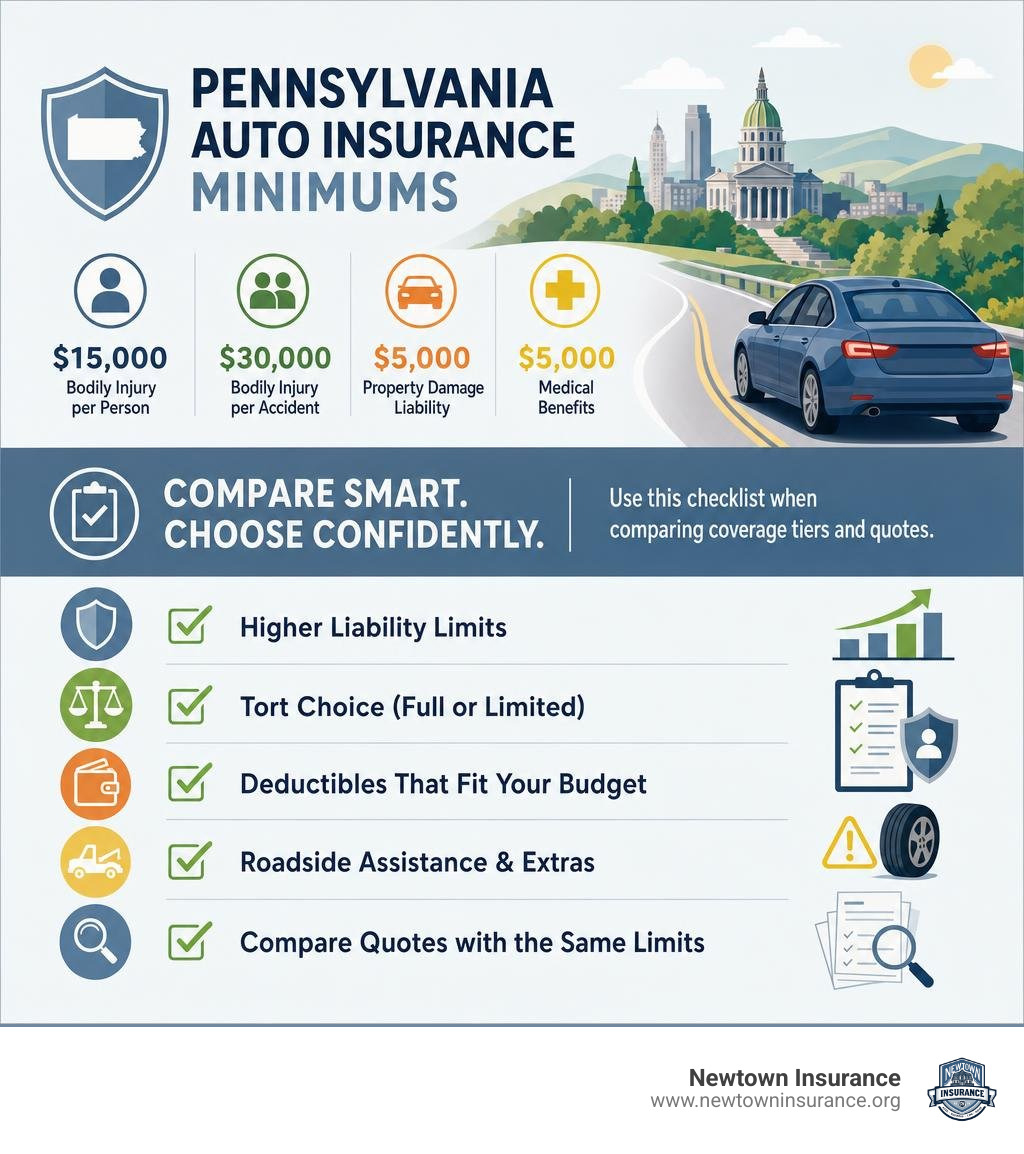
Start by comparing quotes with the same coverage limits. Pennsylvania requires at least $15,000 in bodily injury liability per person, $30,000 per accident, $5,000 in property damage liability, and $5,000 in medical benefits. Those minimums may leave you with large bills after a serious crash, so compare higher limits, your tort choice, deductibles, and any roadside coverage before choosing a policy.
I’m Shawn Beihl. For drivers searching for dependable car insurance in Hershey, PA, I bring over 15 years of insurance experience, including property and casualty, to help make those choices clearer for motorists across Pennsylvania. Newtown Insurance is based in Newtown, PA, and our team works with drivers throughout the Commonwealth, including Dauphin County communities like Hershey, to deliver the same customer-first support and transparent pricing statewide.
Explore our regional Pennsylvania coverage resources:
Pennsylvania Coverage Requirements and Tort Options
When establishing coverage in Dauphin County, understanding state-mandated coverage levels is the starting point. The Commonwealth operates under a unique framework that combines no-fault medical coverage with a choice of tort options. Navigating these mandates ensures you remain road-legal while preventing severe financial exposure if an accident occurs along Hersheypark Drive or Route 322.

Pennsylvania law, overseen by the Pennsylvania Insurance Department, specifies several mandatory protections that must be included in every active auto policy:
- Bodily Injury Liability: A minimum of $15,000 per person and $30,000 per accident to pay for injuries sustained by other parties when you are at fault.
- Property Damage Liability: At least $5,000 to cover repairs or replacement of another person’s vehicle or stationary property.
- First-Party Medical Benefits: A mandatory baseline of $5,000 in personal injury protection (PIP), which pays for medical expenses for you and your passengers regardless of fault.
While these baseline limits satisfy the law, modern vehicle repair bills and hospital costs frequently surpass basic state minimums. In our auto insurance requirements in Pennsylvania breakdown, we emphasize why carrying higher liability limits—such as 100/300/100—protects your personal assets and income from potential litigation. To explore broader coverage structures across multiple policy types, review our ultimate auto insurance guide.
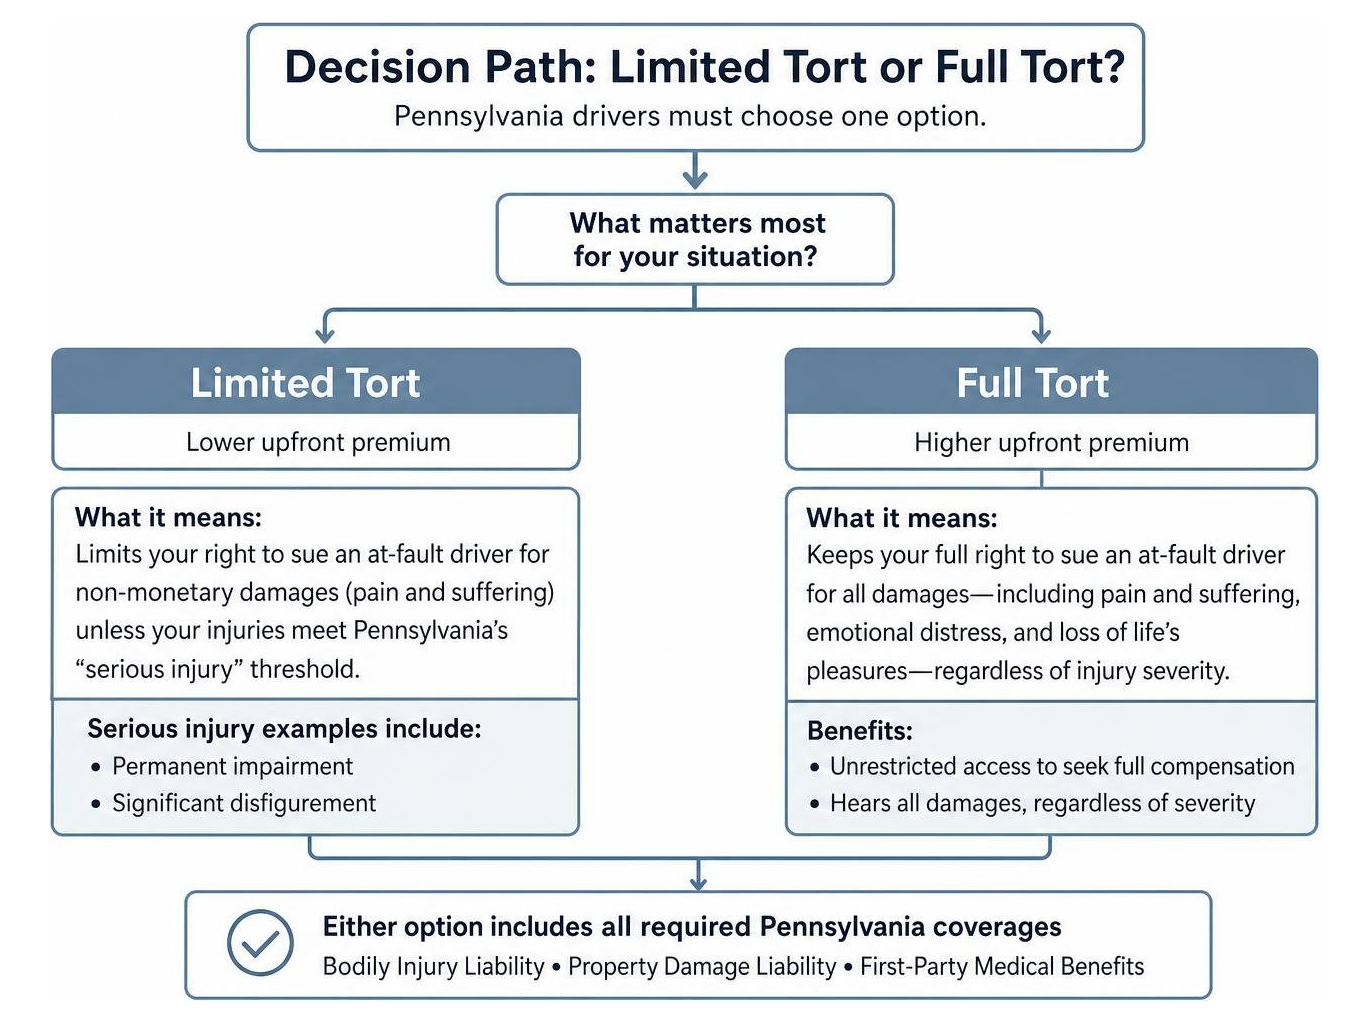
Beyond mandatory coverage minimums, Pennsylvania drivers must choose between two tort options:
- Limited Tort: Choosing this option lowers your annual premium. However, it limits your legal right to sue an at-fault driver for non-monetary damages (such as pain and suffering) unless the injuries meet the state’s legal definition of “serious injury” (e.g., permanent impairment or significant disfigurement).
- Full Tort: Full tort costs more in upfront premiums, but it maintains your unrestricted right to seek legal compensation for all damages—including physical pain, emotional distress, and loss of life’s pleasures—regardless of the severity of the injury.
Understanding Car Insurance Hershey PA Coverage and Average Costs
Premiums in Dauphin County are shaped by regional risk factors including local traffic patterns, seasonal tourism around Hersheypark, and seasonal winter road conditions. Auto insurance costs in Hershey tend to remain moderate compared to high-density metropolitan zones like Philadelphia or Allentown, offering local motorists a favorable balance of rate stability and comprehensive protection.
Local factors impacting regional pricing include:
- Traffic Density and Commuter Corridors: Regular congestion on US-422, Route 39, and local bypasses influences claim frequencies.
- Seasonal Weather: Freezing winter conditions, ice storms, and road salt cause seasonal spikes in minor collisions and windshield damage claims.
- Dauphin County Claim Rates: Overall regional loss ratios, vehicle theft statistics, and litigation trends in Central Pennsylvania keep rates competitive against state averages.
| Geographic Scope | Average Annual Minimum Coverage | Average Annual Full Coverage | Primary Cost Drivers |
|---|---|---|---|
| Hershey, PA (Dauphin County) | $460 – $580 | $1,550 – $1,850 | Commuter traffic, seasonal tourism, winter weather |
| Pennsylvania Statewide | $520 – $640 | $1,780 – $2,100 | Urban claim concentration, legal litigation rates |
| National Average | $620 – $750 | $1,950 – $2,350 | Severe weather, nationwide supply-chain repair inflation |
For a comprehensive evaluation of regional rate factors across the Commonwealth, review our car insurance rates in Pennsylvania benchmark or consult our broader Pennsylvania auto insurance guide.
Choosing the Right Policy Options for Car Insurance Hershey PA Motorists
A resilient policy balances essential baseline liability with physical damage protections. Selecting the right combination shields your finances against unforeseen collisions, property loss, and underinsured drivers.
- Collision Coverage: Pays to repair or replace your vehicle if you collide with another car, a guardrail, or an object, regardless of fault.
- Comprehensive Coverage: Covers non-collision incidents, including deer collisions along rural Dauphin County roads, fallen tree limbs, hail storms, vandalism, and theft.
- Uninsured and Underinsured Motorist Coverage (UM/UIM): Protects you and your passengers if an at-fault driver has no insurance or insufficient liability limits to cover your medical costs.
For drivers looking to protect newer or financed vehicles, balancing comprehensive and collision protection with sensible deductibles delivers affordable full coverage options without unnecessarily inflating monthly costs.
Local Auto Repairs, Insurance Claims, and Roadside Benefits
When an accident occurs, navigating the claims process efficiently relies on working with experienced local repair facilities. In Hershey, reputable auto shops maintain transparent communication channels with major insurance adjusters, which accelerates repair estimates, streamlines digital approvals, and minimizes repair downtime.
Key ways local repair centers streamline your claims experience include:
- Direct Estimating and Billing: Mechanics submit detailed line-item estimates directly to insurance adjusters via integrated claims platforms, avoiding out-of-pocket delays.
- Deductible Clarification: Many facilities help policyholders understand how collision or comprehensive deductibles apply directly at the time of vehicle pickup.
- Original Equipment Manufacturer (OEM) Parts: Established shops help advocate for quality replacement components that meet factory safety specifications.
Certified Repair Facilities and Roadside Service Coverage
Selecting a certified or professionally endorsed auto repair facility provides concrete service guarantees and quality standards for policyholders:
- Rigorous Certification Standards: Facilities undergo evaluations covering technician training, clean diagnostic equipment, professional licensing, and customer satisfaction.
- Priority Battery Diagnostics: Certified facilities provide testing and battery replacement services, often backed by nationwide multi-year limited replacement warranties.
- Integrated Roadside Assistance: Pairing your insurer’s roadside assistance endorsement with certified repair networks ensures prompt towing, tire changes, fuel delivery, and lockout services when stranded.
Proven Strategies to Maximize Policy Savings
Securing strong protection does not require paying excessive premiums. Insurers evaluate risk across several variables, meaning proactive policyholders can systematically apply discounts to reduce overall policy expenses.
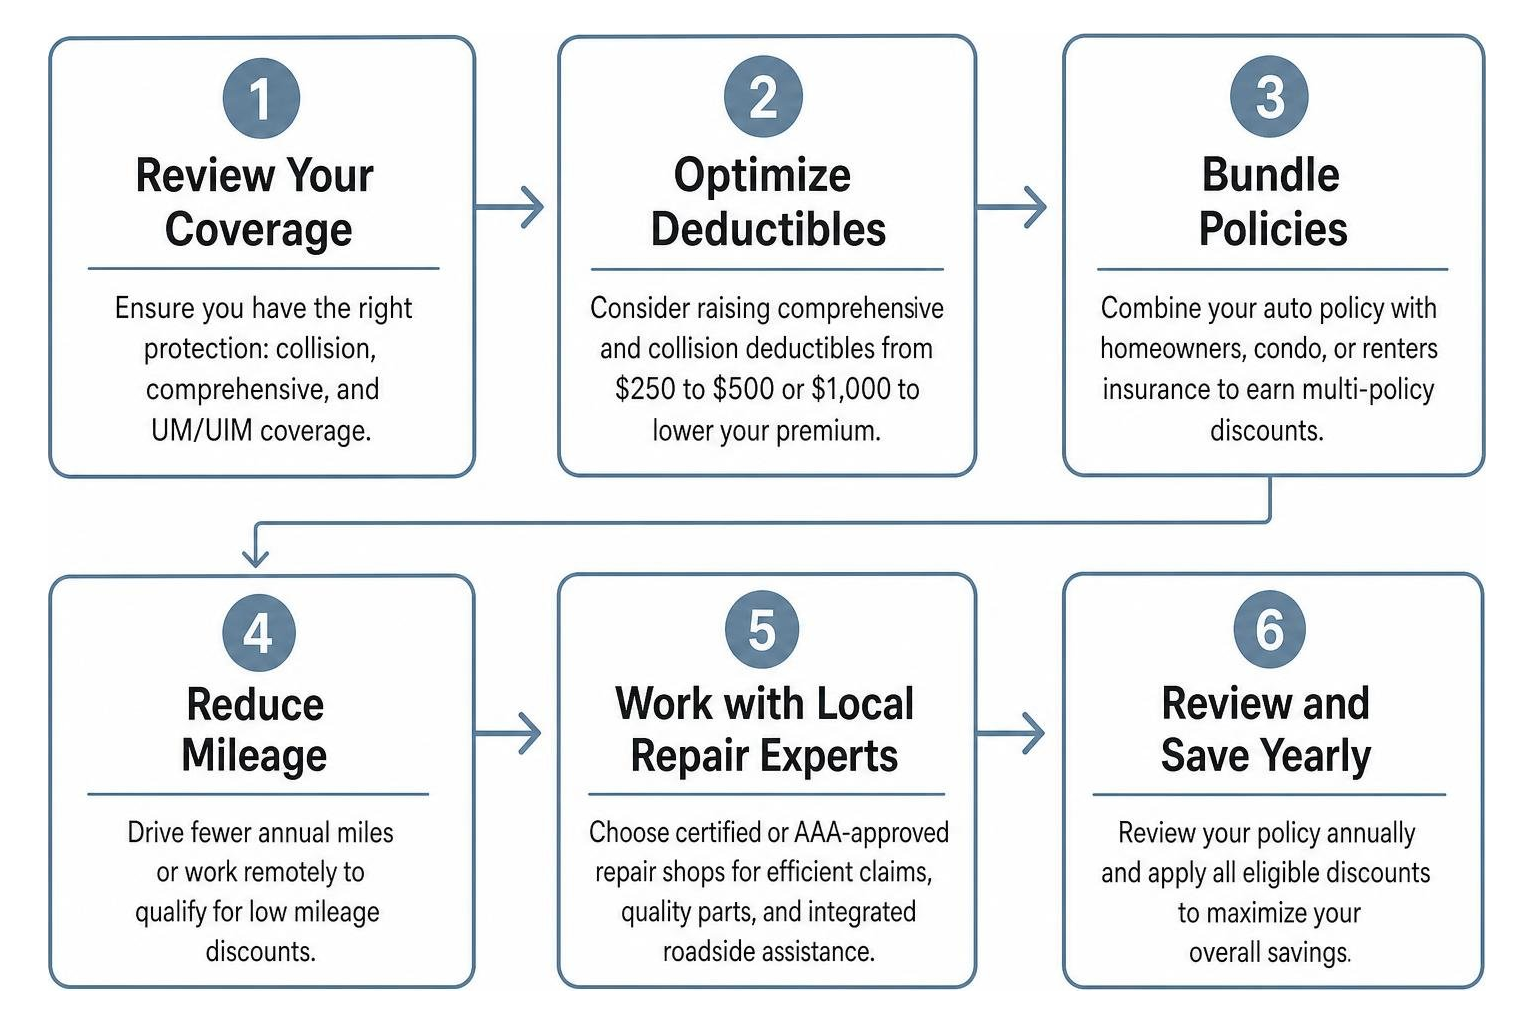
Effective tactics for reducing premiums include:
- Optimizing Deductibles: Raising your comprehensive and collision deductibles from $250 to $500 or $1,000 can lower collision and comprehensive premium portions.
- Multi-Policy Bundling: Pairing your auto policy with homeowners, condo, or renters insurance yields substantial multi-line credits across both policies.
- Low Mileage Discounts: Driving fewer annual miles or working remotely can qualify your vehicles for reduced-usage rating tiers.
To identify every discount you qualify for, explore our detailed auto insurance discount guide and evaluate these valuable car insurance discounts.
Practical Strategies to Lower Car Insurance Hershey PA Premiums
Implementing disciplined driving and shopping habits unlocks sustained savings year over year:
- Maintain a Clean Driving History: Avoiding moving violations and preventable claims keeps you in the preferred risk tier with the lowest base rates.
- Complete a Defensive Driving Course: Voluntary driver training courses often yield state-mandated premium discounts for eligible mature operators.
- Monitor Your Insurance Credit Tier: In Pennsylvania, maintaining strong credit habits positively influences your insurance score and lowers baseline pricing.
- Compare Quotes Regularly: Reassessing your coverage profile ensures your rates remain competitive as market conditions evolve.
To streamline your search for cost-effective coverage, read our advice on securing cheap car insurance, review the anonymous car insurance quote process, or request fast online auto insurance quotes.
Frequently Asked Questions About Hershey Auto Insurance
What is the minimum auto insurance coverage required in Hershey, PA?
Pennsylvania law requires all registered vehicles to carry at least $15,000 of bodily injury liability per person, $30,000 per accident, $5,000 of property damage liability, and $5,000 of medical benefits coverage. Motorists must also select either a limited tort or full tort coverage option on their policy.
How do local Hershey repair shops assist with the insurance claims process?
Local repair centers work directly with insurance appraisers to provide electronic damage estimates, photograph structural damage, file supplemental repair requests, and coordinate billing. This direct communication eliminates paperwork burdens and speeds up vehicle repair turnaround times.
Does auto insurance in Hershey cover battery replacement and towing?
Standard liability policies do not cover battery replacement or towing. However, adding an optional roadside assistance endorsement or towing and labor rider to your policy covers jump-starts, battery diagnostics, winching, and towing to an approved repair facility if your vehicle becomes disabled.
Conclusion
Securing the right auto insurance in Hershey requires balancing essential legal minimums with practical coverage limits that shield your assets. By evaluating tort choices, selecting appropriate deductibles, and leveraging multi-policy discounts, Dauphin County drivers can achieve dependable protection without overpaying. Although Newtown Insurance is headquartered in Newtown, PA, we proudly serve drivers across the Commonwealth, including Hershey and the surrounding Dauphin County area, with the same customer-first support, transparent pricing, and tailored policies that fit your daily driving needs. When you are ready to evaluate your policy options, explore customized Pennsylvania coverage plans with our team.