Understanding How Auto Insurance Glass Coverage Works
Auto insurance glass coverage pays to repair or replace damaged vehicle safety glass, including windshields, side windows, rear windows, and sunroofs. In standard policies, Is Glass Covered Under Comprehensive Car Insurance? Yes—glass damage is covered under comprehensive insurance, which protects against non-collision perils. Under standard comprehensive coverage, repairs or replacements are subject to your comprehensive deductible, whereas an optional dedicated full glass endorsement waives the deductible entirely.
Qualifying non-collision events that damage auto glass include:
- Airborne road gravel and loose pavement debris
- Severe weather events such as hail storms, falling ice, or high winds
- Falling tree branches or debris from overhead structures
- Vandalism, civil commotion, or break-ins where thieves smash side windows
- Animal collisions, such as a bird or deer striking the windshield
- Thermal stress cracks caused by rapid, extreme temperature shifts
It is vital to recognize that liability-only coverage never covers damage to your own vehicle. If you carry only state-mandated minimum liability insurance and a rock shatters your windshield, you will bear 100% of the replacement expense out of pocket.
Comprehensive Policy vs. Dedicated Auto Insurance Glass Coverage
While standard comprehensive insurance pays for damaged auto glass, it is subject to your standard policy deductible—which often sits at $250, $500, or even $1,000. If your comprehensive deductible is $500 and a standard replacement costs $350, filing a regular comprehensive claim offers zero financial benefit.
To bridge this financial gap, insurance providers frequently offer an optional full glass endorsement or a glass deductible waiver. When you secure affordable auto insurance full coverage, adding a dedicated glass endorsement means you pay a $0 deductible for glass claims, even if your main comprehensive collision deductible is much higher.
Here is how standard comprehensive coverage compares to a dedicated full glass endorsement:
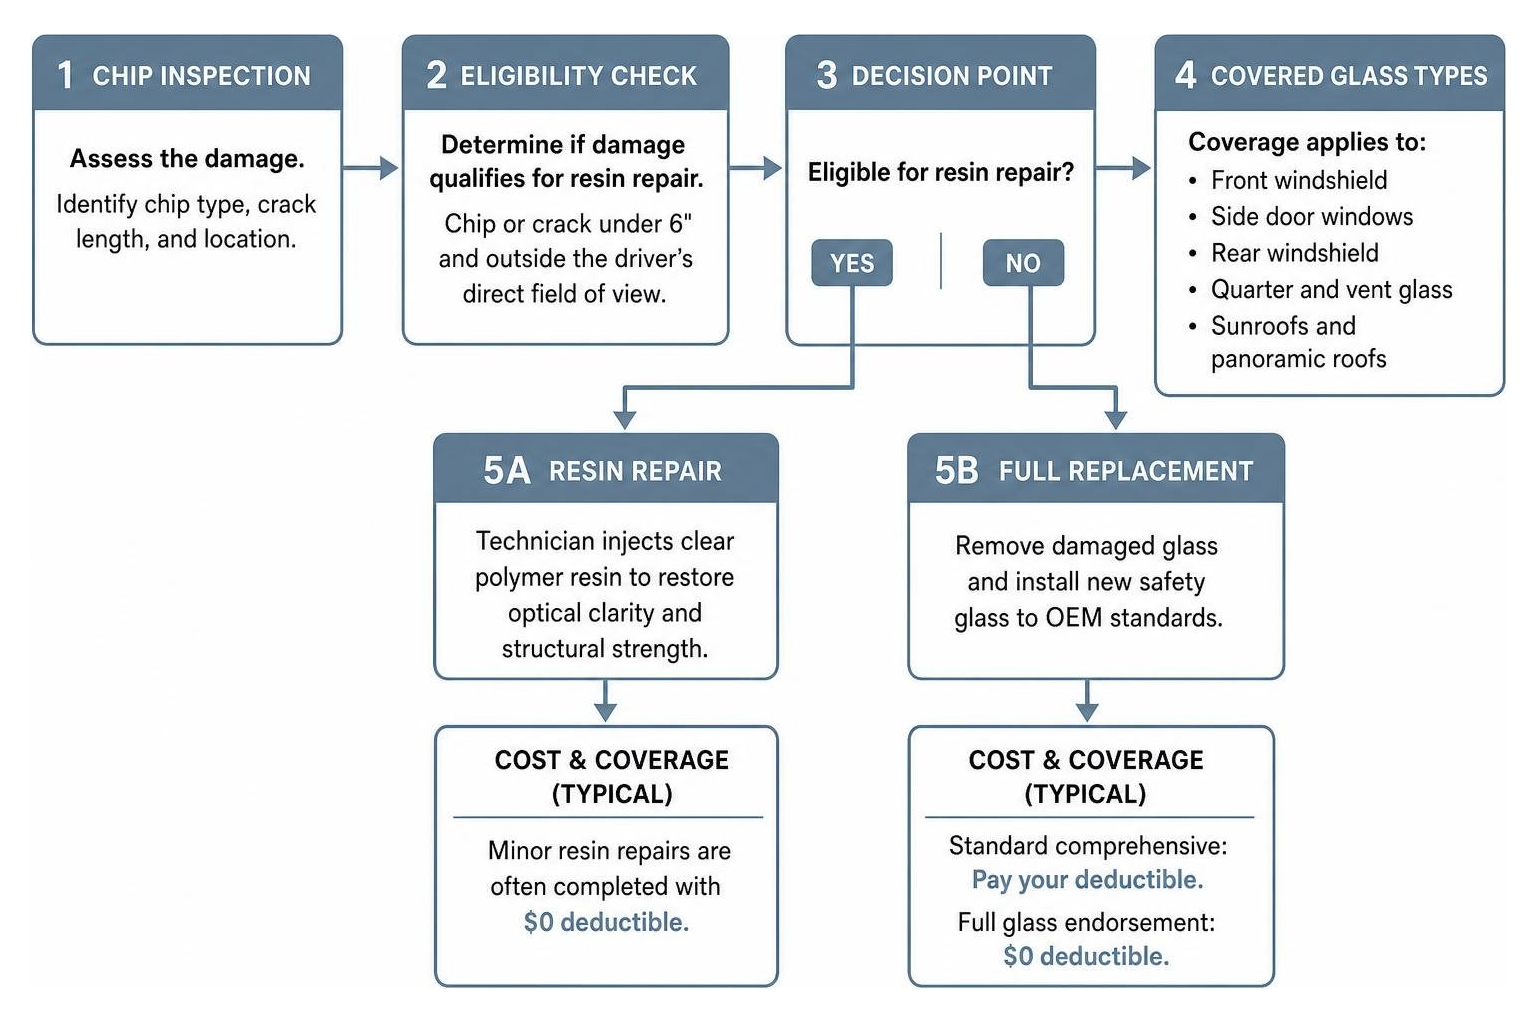
- Standard Comprehensive Glass Coverage: Covers all vehicle glass against non-collision hazards, but you must pay your standard comprehensive deductible before the insurer pays the remainder. Minor resin repairs are often completed with no deductible, but replacements require the full out-of-pocket deductible.
- Full Glass Coverage Endorsement: A supplemental rider attached to comprehensive coverage that waives your deductible entirely for both repair and replacement of safety glass, including windshields, side windows, and rear windows.
Covered Glass Types and Qualifying Incidents
Dedicated auto glass coverage does not stop at the front windshield. Standard comprehensive endorsements typically protect every piece of automotive safety glass installed in your vehicle:
- Front Windshields: Laminated safety glass designed to withstand aerodynamic pressure, support the vehicle roof structure, and shield occupants from debris.
- Side Door Windows: Usually made from tempered glass that shatters into small, blunt cubes upon impact to minimize laceration risks during side collisions or break-ins.
- Rear Windshields (Back Glass): Tempered glass often integrated with defroster grid lines, radio antennas, and rear wiper assemblies.
- Quarter Glass and Vent Glass: Small side panels that complete the passenger cabin’s weather seal and visibility.
- Sunroofs and Panoramic Glass Roofs: Factory-installed glass panels on vehicle roofs (though aftermarket non-factory roof additions may require special custom equipment riders).
When minor damage occurs—such as a bullseye chip, star break, or crack under six inches located outside the driver’s direct field of view—technicians can use clear polymer resin to restore optical clarity and structural strength without removing the glass panel.
Deductibles, State Regulations, and Out-of-Pocket Costs
The amount you ultimately pay out of pocket depends heavily on the state where your policy is written, the wording of your contract, and your deductible tier. Does Insurance Cover Windshield Replacement By State? The rules vary significantly across state lines, creating widespread confusion among drivers who relocate or travel.
| State Regulatory Model | Representative States | How the Deductible Operates |
|---|---|---|
| Mandatory Zero-Deductible Mandate | Florida, Kentucky, South Carolina | State statute requires insurers to waive deductibles for safety glass replacement under comprehensive policies ($0 out of pocket). |
| Mandatory Endorsement Offer | Arizona, Connecticut, Minnesota, New York | State law requires insurers to make separate zero-deductible full glass coverage available for purchase as an optional rider. |
| Standard Comprehensive Model | Pennsylvania, Texas, Colorado, and most others | No statutory zero-deductible mandate; standard comprehensive deductibles apply unless the policyholder chooses to buy a zero-deductible glass endorsement. |
Zero-Deductible States and Legislative Rules
A handful of states have enacted specific statutory protections regarding auto glass deductibles. In Florida, under Florida Statute 627.7288, insurers writing comprehensive policies cannot apply a deductible to windshield repairs or replacements. However, this waiver applies strictly to the front windshield—side and back glass remain subject to standard comprehensive deductibles. Following legal reforms in 2023, Florida also eliminated the Assignment of Benefits (AOB) mechanism for auto glass claims to reduce litigation abuse.
In Kentucky and South Carolina, comprehensive policies historically include mandatory zero-deductible safety glass provisions across all automotive glass. In Arizona, state law requires insurers to offer an optional zero-deductible glass rider, though it is not automatically granted for free.
If your policy is written in Pennsylvania, you follow the standard comprehensive model. State law does not mandate a free windshield replacement. To understand how your local policy safeguards your vehicle against road hazards, our comprehensive Pennsylvania auto insurance guide 2026 outlines regional deductible rules and coverage limits.
Factors That Influence the Cost of Auto Insurance Glass Coverage
Adding full auto insurance glass coverage to your comprehensive policy is generally very affordable. On average, a standalone full glass endorsement adds roughly $5 to $10 per month ($60 to $120 per year) to your overall auto insurance premium.
Key factors influencing this cost include:
- Vehicle Make, Model, and Trim: Luxury vehicles, vehicles with large panoramic sunroofs, or cars fitted with heads-up displays carry higher replacement part costs, moderately increasing endorsement premiums.
- Advanced Driver Assistance Systems (ADAS): Vehicles housing forward-facing safety cameras and radar brackets behind the windshield require technical calibration, raising total claim loss projections.
- Annual Driving Mileage: Commuters logging higher mileage face higher aggregate exposure to loose road gravel, which slightly alters comprehensive rating tiers.
- Selected Deductible Level: Choosing a policy with a higher comprehensive baseline deductible lowers your standard monthly premium, while adding a glass waiver ensures minor road chips do not trigger surprise out-of-pocket costs. To balance baseline deductibles against policy riders effectively, check our auto insurance savings complete guide.
Repair vs. Replacement, ADAS Recalibration, and Glass Types
When damage strikes, evaluating whether the glass can be repaired or must be completely replaced is the first technical decision.
A windshield can generally undergo resin repair if:
- The rock chip or bullseye break is smaller than a quarter (roughly one inch in diameter).
- A linear crack measures less than six inches in length.
- The damage is positioned completely outside the driver’s acute viewing area (direct line of sight).
- The outer layer of laminated glass is cracked, but the inner polyvinyl butyral (PVB) safety interlayer remains unpunctured.
- The break does not touch or compromise the outer edge of the windshield frame.
If a crack extends to the edge of the glass, branches out in multiple directions, or obstructs the forward-facing camera system, full replacement is mandatory. The typical cost to repair a windshield ranges from $60 to $150. If replacement is needed, the average cost for standard vehicles runs between $200 and $400, but can easily exceed $1,000 for modern vehicles equipped with active safety technology.
The Critical Role of ADAS Sensor Recalibration
Modern vehicles rely on Advanced Driver Assistance Systems (ADAS) to operate essential active safety features, such as:
- Forward collision warning and autonomous emergency braking
- Lane departure warning and lane-keeping assistance
- Adaptive cruise control and speed sign recognition
- Pedestrian detection sensors
These systems depend directly on precision cameras, LiDAR, and radar units mounted directly behind the upper portion of the windshield. When an old windshield is removed and a new one is set into place, the microscopic optical alignment of those cameras changes. A camera misaligned by even a fraction of a degree can throw off distance calculations down the road by several yards.
Recalibration after windshield replacement usually costs between $300 and $600, though some specialty setups run higher. The ADAS calibration market has grown into a $2.2 billion industry in 2023, projected to reach $7.9 billion by 2028.
There are two primary types of recalibration:
- Static Calibration: Performed inside a controlled workshop setting using precision-placed target boards, lasers, and level flooring to realign cameras according to exact manufacturer geometric specifications.
- Dynamic Calibration: Performed by connecting diagnostic scanning tools to the vehicle’s onboard computer and driving the car at designated speeds on well-marked roadways under specific environmental conditions.
Comprehensive insurance policies cover necessary ADAS recalibration when it is documented as a required safety procedure following a covered glass replacement.
OEM vs. Aftermarket Glass Specifications
When scheduling a full windshield replacement, you will encounter two primary categories of auto glass:
- Original Equipment Manufacturer (OEM) Glass: Fabricated by the exact manufacturer contracted by the vehicle maker. It matches the original factory windshield in thickness, acoustic lamination, solar tinting, curvature, and camera mounting bracket tolerances.
- Aftermarket Glass (Original Equipment Equivalent / OEE): Manufactured by independent glass companies. While legally required to meet Federal Motor Vehicle Safety Standard No. 205 (FMVSS 205) for structural strength and light transmittance, it may exhibit slight variations in bracket dimensions, acoustic insulation, or head-up display clarity.
Insurers generally agree to pay for “like kind and quality” parts, which standardly allows the use of certified aftermarket glass. However, if you drive a late-model vehicle, a leased vehicle, or a car with complex heads-up display (HUD) projections, your insurer may approve OEM glass if documented that aftermarket options fail to calibrate properly with the vehicle’s safety sensors.
Claims, Shop Selection, and Cash vs. Insurance Decisions
Deciding whether to file an insurance claim or pay out of pocket comes down to simple math and policy protection.
Before filing an auto glass claim, evaluate the following:
- Compare Total Cost vs. Your Deductible: If a new windshield costs $350 out of pocket and your comprehensive deductible is $500, filing a claim makes no sense because insurance will pay $0.
- Presence of Advanced Driver Assistance Systems: If your vehicle has forward-facing cameras requiring $400 in static recalibration on top of a $500 windshield, the total bill ($900) easily justifies filing a claim against a $250 or $500 deductible.
- Claim-Free Discount Protection: If you currently earn a substantial claim-free discount across your auto policy, filing a low-dollar $150 claim could forfeit a discount worth far more over a multi-year policy term. Explore our auto insurance discounts guide 2026 to calculate how claims impact your overall rate structure.
- Claim Frequency History: While a single no-fault comprehensive glass claim rarely increases premiums, having three or more comprehensive claims within a rolling 36-month window can cause underwriters to reclassify your risk profile.
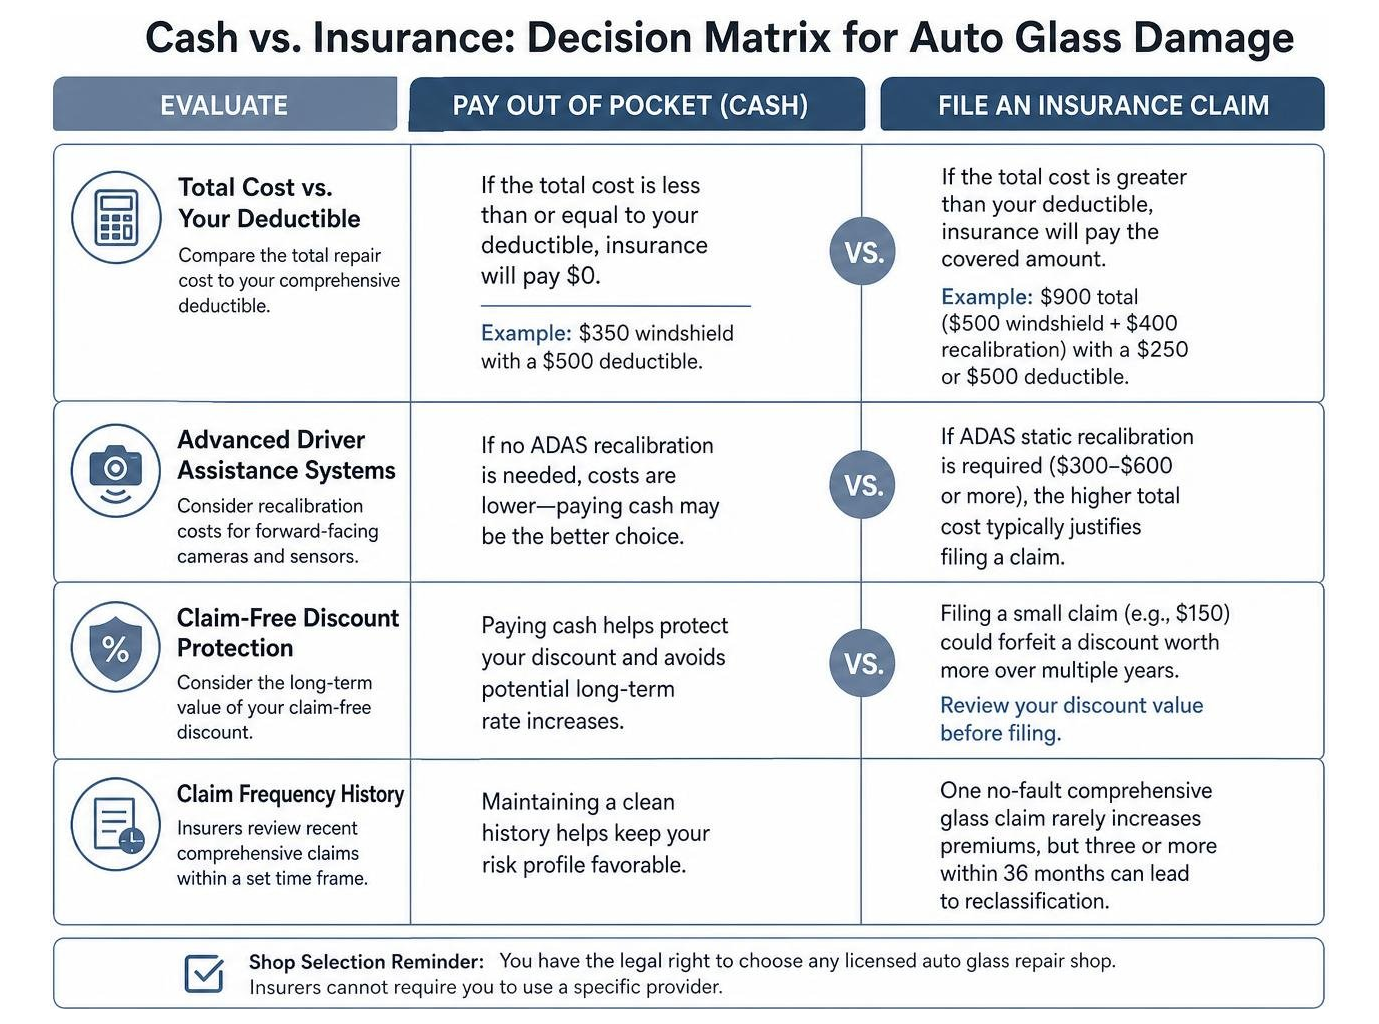
When it comes to repair shop selection, state anti-steering regulations protect your legal right to choose any licensed auto glass repair facility. While insurance representatives may recommend national network glass clearinghouses with pre-negotiated direct billing, they cannot legally compel you to use a specific repair shop.
Frequently Asked Questions About Auto Glass Insurance
Will filing a single windshield claim increase my auto insurance rates?
Generally, no. Auto insurance glass coverage claims are filed under comprehensive insurance, which categorizes losses as no-fault, non-collision incidents. Because road gravel, weather, and falling tree limbs are unpredictable acts outside driver control, insurers rarely apply surcharges for an isolated glass claim.
However, excessive claim frequency can influence renewal pricing. If you file multiple comprehensive claims within a short timeframe (such as three claims in 18 months), underwriters may adjust your risk tier or raise your base comprehensive deductible at policy renewal.
Can my insurance company force me to use their preferred glass repair shop?
No. State consumer protection and anti-steering laws protect your right to select the repair facility of your choice. While your insurance provider may recommend a preferred in-network glass vendor that offers streamlined claims integration and direct billing, you have the legal right to work with any certified local glass technician.
If you select an independent shop outside your insurer’s network, ensure their labor rates align with reasonable, prevailing market rates to avoid paying unexpected out-of-pocket balance differences.
How long does a windshield replacement take and when can I safely drive?
A standard mobile or in-shop windshield replacement typically takes 60 to 90 minutes to complete. If your vehicle requires static or dynamic ADAS sensor recalibration, plan for an additional 30 to 60 minutes of diagnostic setup and road testing.
After the glass is installed, you must observe the Safe Drive-Away Time (SDAT). Modern polyurethane urethane adhesives require between 30 minutes to 2 hours of curing time before the vehicle can be safely driven. This cure time is vital: your windshield contributes up to 30% of a vehicle’s structural roof strength during rollover accidents and acts as the backstop for proper passenger airbag deployment. Always confirm the adhesive manufacturer’s specified cure time with your technician before driving away.
Conclusion
Understanding how auto insurance glass coverage safeguards your vehicle ensures that a sudden crack on the road does not disrupt your budget or compromise your safety. Ensuring that your policy includes comprehensive protection with a zero-deductible glass waiver gives you peace of mind whether you need a quick resin chip fill or a full camera-recalibrated replacement.
At Newtown Insurance, our team in Newtown, Pennsylvania is dedicated to delivering tailored protection, transparent pricing, and customer-first support. We help you navigate policy endorsements so you never overpay for coverage you don’t need while staying completely protected against unexpected road hazards.
If you want to review your current policy limits or explore full glass coverage endorsements, visit our services and personalized insurance quotes page today to speak with one of our experienced local advisors.