Compare Personal Trainer Insurance Quotes Before You Train
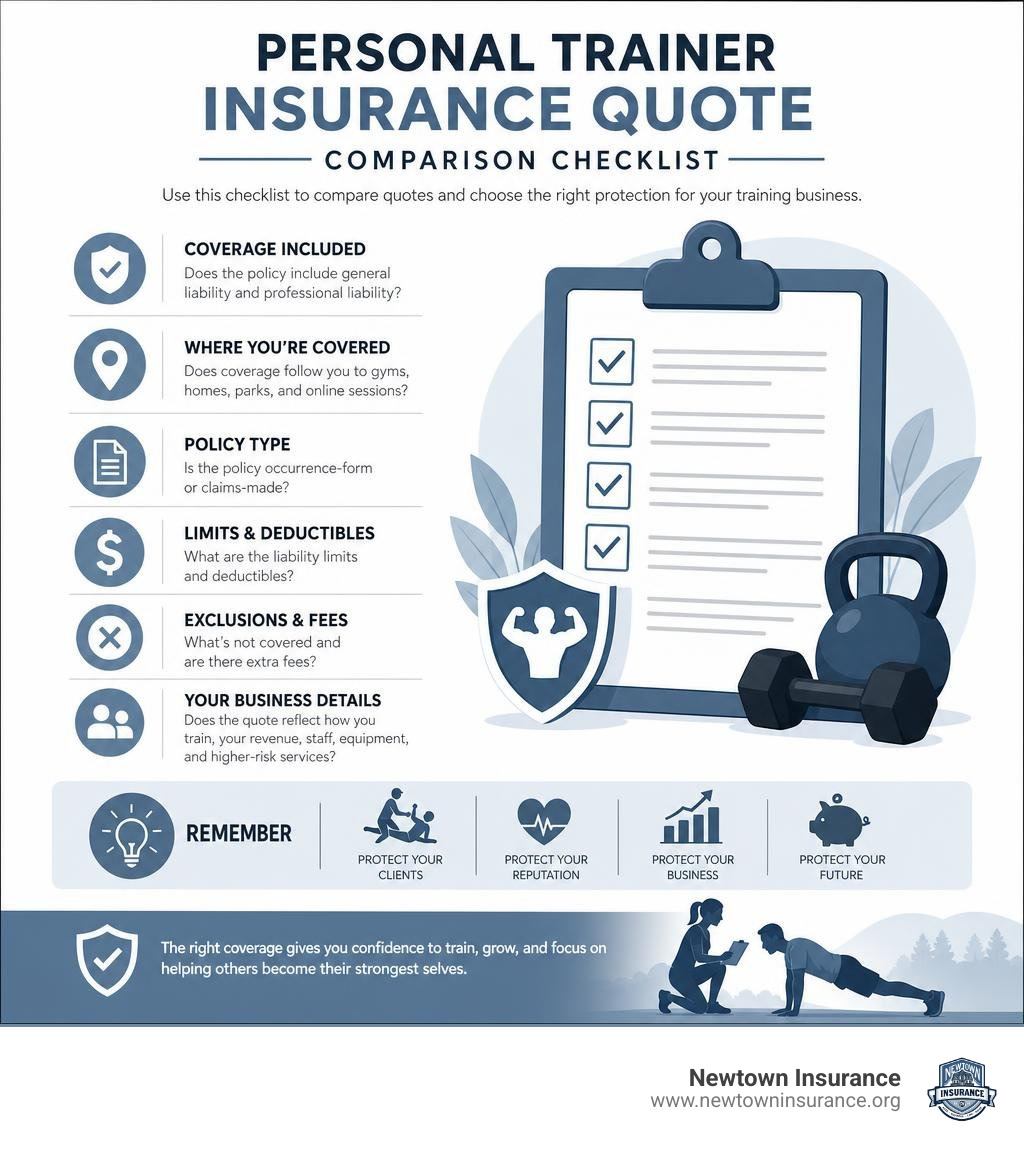
To get useful personal trainer insurance quotes, compare policies that include at least general liability and professional liability coverage. Ask each insurer to confirm the liability limits, whether coverage follows you to gyms, homes, parks, and online sessions, and whether the policy is occurrence-form or claims-made.
A low price matters, but so do exclusions and fees. A client could be injured during a lift, trip over your equipment, or claim your training plan caused harm. Fitness liability claims can be expensive, with the average claim estimated at about $25,000.
Your quote should reflect how and where you train, your certifications, annual revenue, staff or subcontractors, equipment, and any higher-risk services you offer. If you work at a gym, request a Certificate of Insurance and check whether the gym needs to be listed as an additional insured.
I am Shawn Beihl of Newtown Insurance, with more than 15 years of experience in specialty insurance, commercial property and casualty coverage, benefits, and risk management. I help business owners assess personal trainer insurance quotes with a focus on clear coverage, practical loss prevention, and long-term cost control.
Essential Coverage Types in Personal Trainer Insurance Quotes
When building a successful fitness career, your energy should be spent motivating clients and perfecting programming—not worrying about potential lawsuits. Working in fitness comes with inherent physical risks. According to the National Safety Council, despite a 27% decrease in overall recreational and sports-related injuries in recent years, nearly 400,000 injuries still occur annually involving physical exercise and exercise equipment.
Selecting the right business insurance coverage is the bedrock of protecting your livelihood. Whether you train clients out of a local private studio in Newtown, Pennsylvania, travel to their living rooms, or host boot camps in public parks, understanding your baseline protection requirements prevents severe financial fallout from third-party bodily injury and property damage claims.
General Liability and Professional Liability Foundations
A comprehensive fitness insurance package relies on two core pillars: General Liability and Professional Liability. While they might sound similar, they cover entirely distinct liabilities.
- General Liability Insurance: This covers standard slip-and-fall accidents and third-party property damage. For example, if a client trips over a 20-pound kettlebell you left on the studio floor and fractures their wrist, or if you accidentally knock over and shatter an expensive display while demonstrating lunges in a client’s home, general liability steps in to pay for medical bills, repairs, and legal defense costs.
- Professional Liability Insurance (Errors & Omissions): In the fitness world, this is effectively your malpractice insurance. It protects you against allegations of improper technique instruction, poor nutritional advice, failure to progress a client safely, or designing a workout routine that exacerbates a pre-existing condition. If a client tears a rotator cuff during an overhead press because they claim your cueing was negligent, professional liability covers your legal defense and any resulting settlements. Finding dedicated professional liability coverage ensures your specialized programming remains protected.
Securing dedicated liability insurance PA ensures you are covered against both physical accidents on the premises and allegations regarding the quality of your professional instruction.
Specialized Add-Ons for Equipment, Workers’ Comp, and Cyber Risks

While general and professional liability form the foundation, fitness professionals often need supplemental coverage tailored to their business structure:
- Commercial Property and Equipment Coverage: Standard liability policies do not protect your own gear. If you travel with battle ropes, suspension trainers, dumbbells, or electronic diagnostic devices, securing specialized business equipment insurance protects your investment against theft, loss, or transit damage.
- Workers’ Compensation: If you hire assistants, apprentice trainers, or administrative staff, carrying workers compensation insurance PA is legally mandated in Pennsylvania. Even sole proprietors often elect this coverage to ensure their own medical expenses and lost wages are covered if they suffer a career-pausing injury while working with a client.
- Cyber Liability and Identity Theft Protection: If you collect payment information, store digital health intake forms, or use client management apps, cyber coverage protects you against data breaches. Some specialized policies also package identity theft restoration benefits to safeguard your personal credentials.
- Commercial Auto Insurance: Personal auto policies rarely cover business-use accidents. If you drive between clients’ homes or transport heavy fitness equipment in your vehicle, commercial auto coverage bridges this critical gap.
What Influences Policy Costs and Pricing Benchmarks
Personal training insurance is remarkably budget-friendly compared to the thousands of dollars an unexpected liability claim could cost your business. Industry data shows that personal trainers pay a median of $600 per year for general liability insurance and a median of $900 per year for standalone professional liability coverage. However, bundled packages specifically built for solo instructors can start much lower—often between $189 and $250 annually for basic coverage limits.
Securing affordable business insurance depends on understanding standard policy limits and choosing options that match your actual risk exposure.
| Coverage Level | Typical Policy Limits (Occurrence / Aggregate) | Average Annual Cost Range | Best Suited For |
|---|---|---|---|
| Basic Solo Tier | $1,000,000 / $2,000,000 | $189 – $270 | Independent trainers, park boot camps, part-time coaches |
| Standard Professional | $1,000,000 / $3,000,000 | $300 – $600 | Full-time trainers, studio renters, hybrid virtual instructors |
| Comprehensive Studio / High-Limit | $2,000,000 / $5,000,000+ | $700 – $1,200+ | Studio operators, trainers employing staff, high-traffic gyms |
Key Factors That Impact Personal Trainer Insurance Quotes
Insurers evaluate several risk factors when calculating your premium:
- Professional Certifications: Holding an accredited credential from recognized bodies such as the National Academy of Sports Medicine (NASM), the American Council on Exercise (ACE), or the National Strength and Conditioning Association (NSCA) can lower your rate. Many underwriters offer discounts—such as 6% or more—to certified trainers because documented credentials establish clear defensibility against negligence claims. Exploring certified fitness instructor insurance options can help you unlock lower tiers.
- Modality and Specialty Areas: Standard strength and conditioning or aerobic instruction carry standard baseline pricing. High-risk activities, such as aerial yoga, full-contact martial arts, or gymnastics coaching, may require specialized underwriting riders.
- Business Revenue and Client Volume: Higher client turnover increases foot traffic and claim probability, which can adjust aggregate premiums upwards.
- Deductibles and Coverage Limits: Choosing higher per-occurrence limits ($2 million vs. $1 million) or lowering your out-of-pocket deductible will slightly increase your annual premium.
Occurrence-Form vs. Claims-Made Coverage Explained
Understanding policy structure is just as critical as the price tag. Fitness liability policies are generally written in one of two forms:
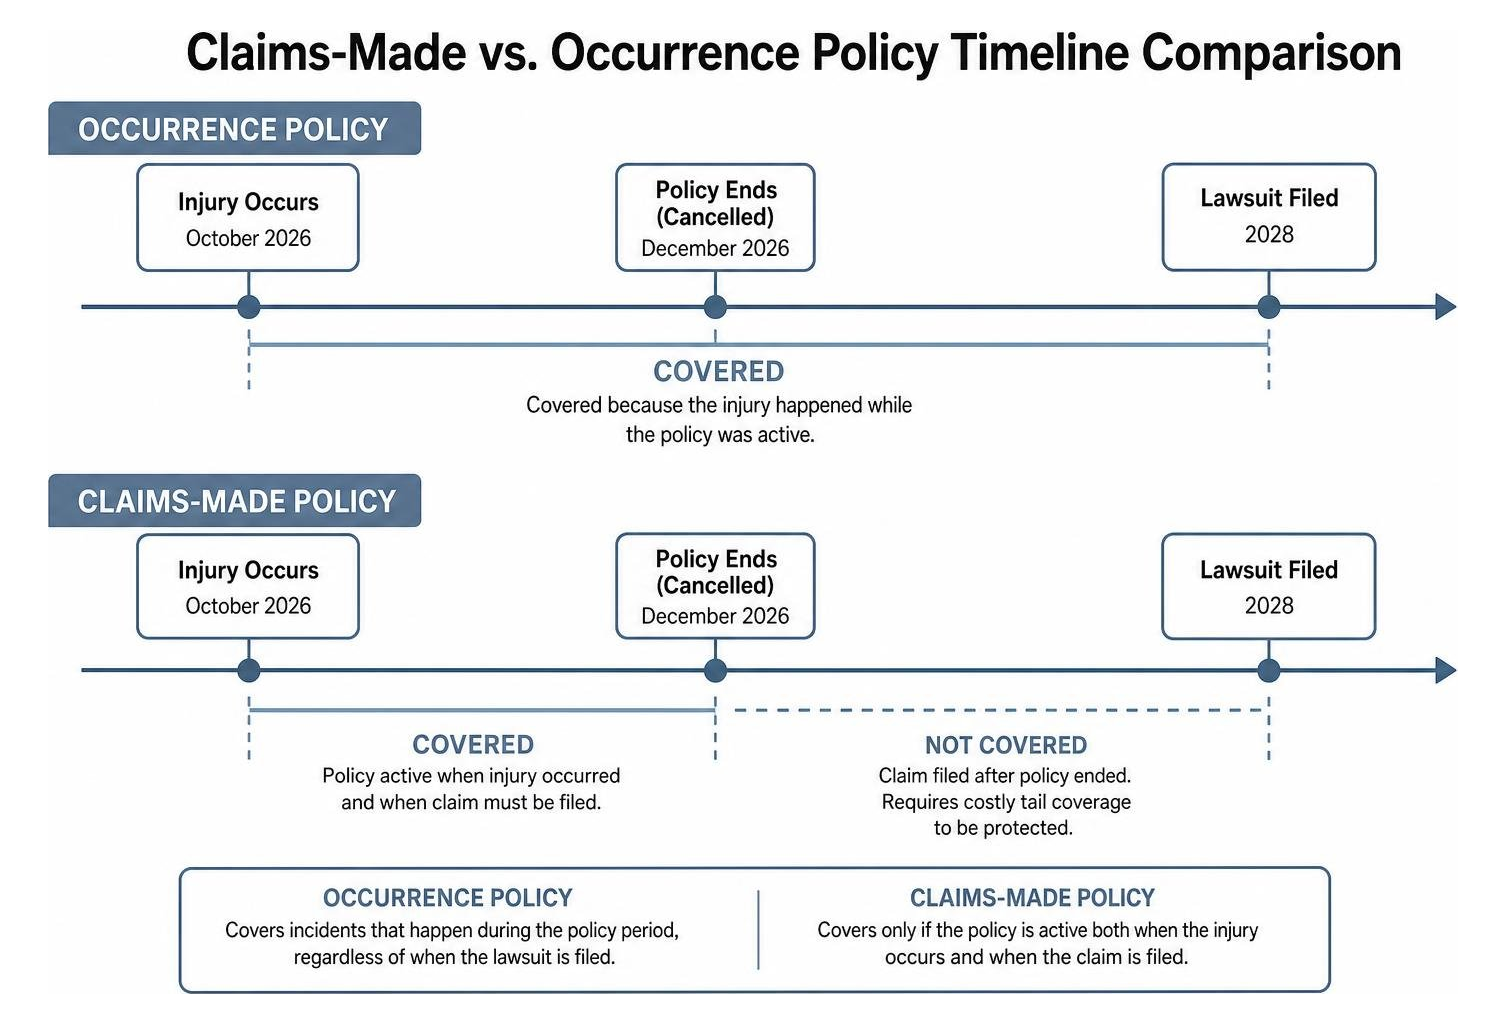
- Occurrence-Form Policies: An occurrence policy covers incidents that happen during the active policy period, regardless of when the lawsuit is actually filed. If a client sustains a joint injury during a session in October 2026, but does not file a lawsuit until 2028, your 2026 occurrence policy handles the claim even if you have since cancelled the policy. This format is widely recommended for fitness pros.
- Claims-Made Policies: A claims-made policy only covers you if the policy is active both when the injury occurs and when the formal claim is submitted to the insurer. If you cancel a claims-made policy without purchasing expensive “tail coverage,” any late-filed lawsuits will be completely uninsured.
For a deeper dive into these policy mechanics, check out our guide on personal liability insurance quotes explained without the headache to choose the right structure with confidence.
Evaluating Independent Risks and Training Environments
Every training environment presents unique hazards. A personal trainer operating outdoors must manage unpredictable terrain, weather, and public bystanders, whereas an in-home trainer must navigate close quarters and client property.

Steps to Request Accurate Personal Trainer Insurance Quotes
To obtain fast, accurate quotes without underwriting delays, follow these proactive steps:
- Gather Business Details: Have your entity structure (Sole Proprietorship, LLC), tax identification number, contact information, and estimated annual gross revenue ready.
- Document Your Credentials: Keep digital copies of your active certifications (NASM, ACE, CPR/AED) on hand.
- Define Your Service Scope: Clarify whether you offer in-person personal training, group fitness, virtual sessions, or nutritional guidance.
- Compare Multiple Options: Review our comprehensive compare insurance quotes complete guide to evaluate multiple policy limits, deductibles, and customer satisfaction metrics side by side before binding coverage.
Working as an Independent Contractor vs. Gym Employee
One of the most dangerous misconceptions in the fitness industry is assuming your facility’s master insurance policy protects you.
- Gym Employees (W-2): Direct employees are generally defended by the gym’s master policy for incidents occurring during scheduled shifts. However, this coverage strictly stops when you step off the clock or work with clients independently outside the facility.
- Independent Contractors (1099): If you pay floor rent or receive a 1099 tax form, commercial facility policies almost universally exclude your personal liability. If an injured client sues you, the gym’s legal team will defend the facility and leave you personally responsible for legal fees and damages.
Commercial gyms require contractors to present a Certificate of Insurance naming the gym as an Additional Insured. Review our contractor insurance Pennsylvania guide to properly structure these endorsements.
Coverage Protocols for Remote and Hybrid Sessions
Digital coaching has transformed fitness, but it introduces distinct legal vulnerabilities. If you train clients over Zoom, FaceTime, or specialized apps, ensure your policy includes explicit digital fitness provisions:
- Live Interactive Streaming vs. Pre-Recorded Videos: Most liability underwriters cover live, two-way interactive virtual sessions where you can observe form and offer real-time corrections. Pre-recorded on-demand video libraries frequently require specialized media liability or digital product endorsements.
- Digital Onboarding & Intake: Always administer digital Physical Activity Readiness Questionnaires (PAR-Q) and obtain signed electronic assumption-of-risk waivers prior to the first virtual workout.
- Cross-Border Considerations: Ensure your domestic policy covers remote clients residing across different states. Exploring broader commercial insurance PA protections ensures your digital operations remain compliant.
Frequently Asked Questions About Fitness Instructor Coverage
Does standard trainer insurance cover online and virtual sessions?
Yes, most modern personal trainer liability policies cover live, two-way interactive virtual sessions. However, coverage often requires you to maintain client intake documentation and conduct workouts in real-time. Pre-recorded, on-demand video programs sold broadly to the public may require additional media liability coverage.
Why do fitness professionals need their own coverage if their gym is insured?
Gym insurance is designed to protect the gym owners and corporate entities—not independent personal trainers. If you are classified as an independent contractor (1099) or train clients outside your scheduled facility hours, you are personally liable for client injuries, equipment accidents, and legal defense costs.
How quickly can fitness trainers receive a Certificate of Insurance?
With modern digital insurance binding, you can typically receive an electronic Certificate of Insurance (COI) immediately upon policy purchase. This allows you to add facility owners as additional insureds and show instant proof of coverage to start training clients right away.
Conclusion
Building a sustainable, thriving fitness business requires smart risk management. While staying focused on your clients’ strength and wellness, having the right insurance ensures a single dropped weight, torn tendon, or slip-and-fall claim won’t derail your career.
At Newtown Insurance, we provide straightforward, transparent guidance to help fitness instructors across Pennsylvania secure optimal coverage without paying for unnecessary fluff. To explore tailored solutions designed around your specific training modalities, visit our services page and connect with our team today.