How Home and Auto Insurance Bundles Work for Property Owners
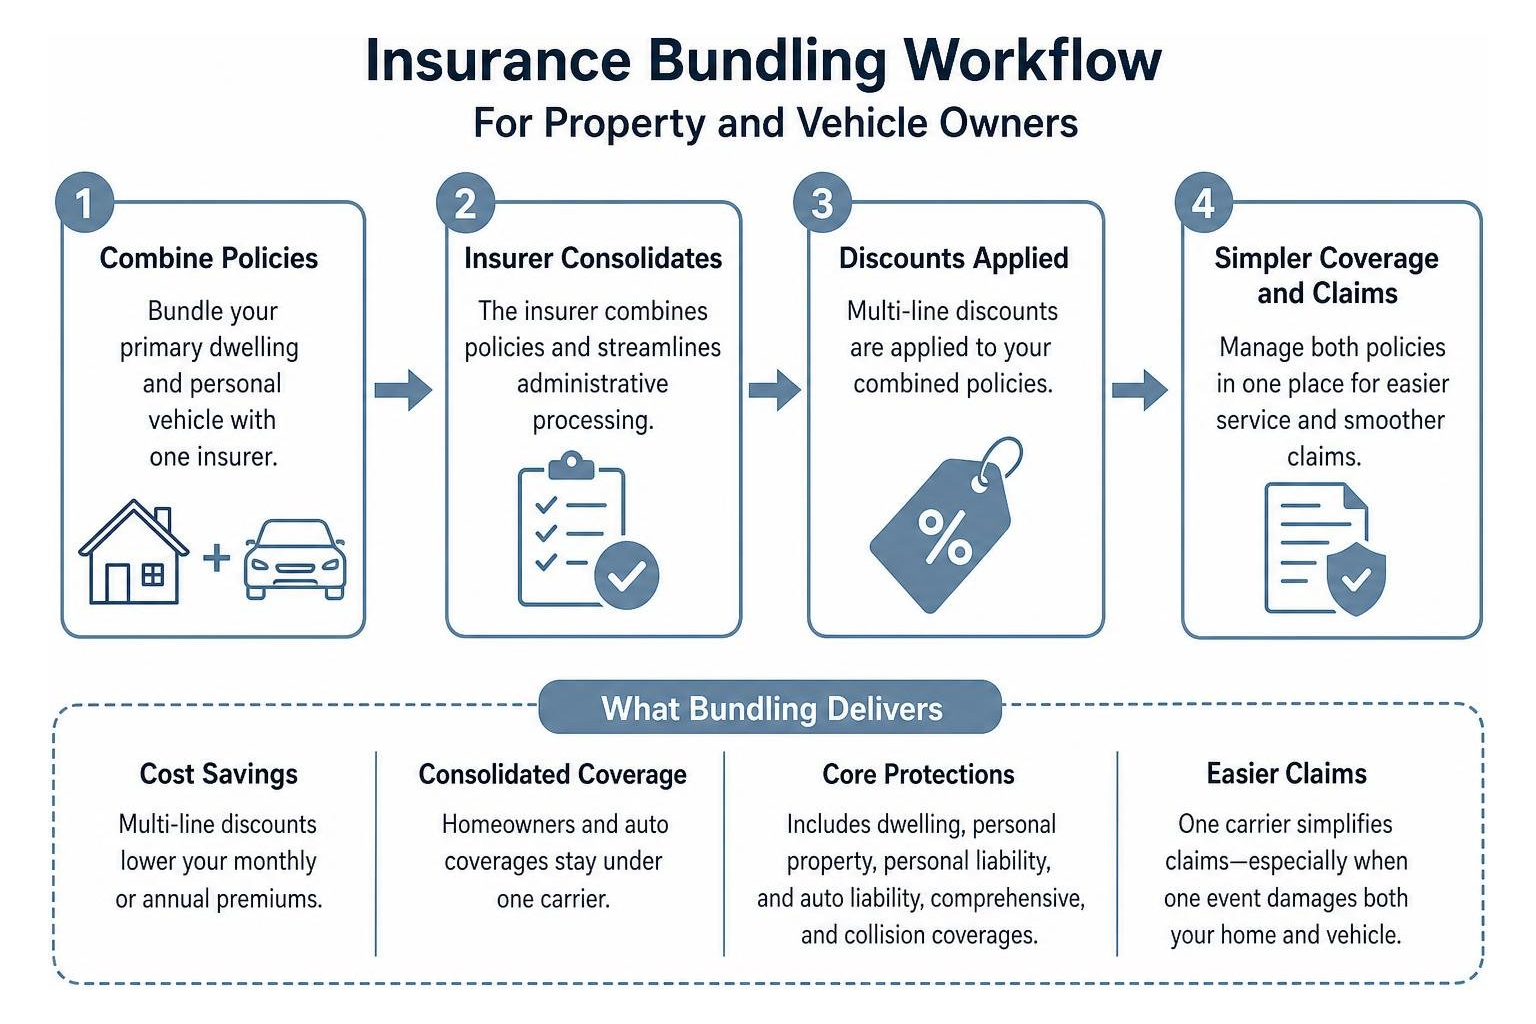
When rural property owners start looking for a farmers bundle quote, they are usually searching for practical ways to combine home, auto, and agricultural coverages with one insurance provider. Throughout this guide, that phrase is used only in its ordinary, generic sense — referring to insurance bundles designed for farmers and rural property owners — not as a reference to any specific insurance company or brand. Property owners and drivers typically save between 10% and 25% on combined annual premiums by consolidating their home, auto, and agricultural coverages under a single carrier. Managing multiple insurance policies across separate companies often leads to unnecessary expenses, overlapping coverages, and administrative headaches. At its core, an Auto and Home Bundle simplifies risk management by placing both your personal vehicle and residential dwelling under a single carrier. In exchange for your combined business, insurance carriers apply multi-line discounts directly to your annual premiums.
When you package your personal vehicle and primary dwelling together, the insurer consolidates administrative processing. That reduced overhead turns into direct savings on your monthly or annual bills. A standard homeowners policy provides core protections, including dwelling coverage (the physical structure of your house), personal property coverage (furniture, clothing, and home contents), and personal liability protection. This personal liability shields you if a guest trips on your walkway or if you accidentally cause property damage away from home.
On the vehicle side, bundling keeps your liability, comprehensive, and collision coverages under the same roof. If a severe storm rolls through Pennsylvania and damages both your parked car and the roof of your house, working with a single carrier makes the claims process significantly smoother. In some cases, carriers even offer a single deductible for events that damage multiple insured assets at the same time.
Standard Multi-Policy Packaging vs Agricultural Risk Endorsements
A standard personal bundle works well for traditional homeowners. However, when property owners engage in agricultural activities – whether managing a small hobby farm, running an equestrian facility, or operating a commercial crop farm – a standard homeowners policy is rarely enough. Traditional homeowners insurance forms (like the standard HO-3) specifically exclude business pursuits, commercial liability, and structures used for farming operations.
To bridge this gap, property owners must understand how personal coverage differs from agricultural endorsements:
- Dwelling Protection: Standard policies protect the main home, while farm packages cover farm dwellings alongside specialized living spaces for farmhands.
- Outbuildings and Barns: Traditional policies offer limited coverage for detached structures (typically 10% of the dwelling limit), which is insufficient for large machinery sheds or livestock barns.
- Vehicles: Our Personal Vehicle Insurance Guide 2026 details how personal cars differ from vehicles used for commercial hauling, livestock transit, or farm utility.
- Liability: Personal liability explicitly excludes claims arising from the sale of produce, livestock injuries, or farm machinery accidents on public roads.
Agricultural endorsements modify the base policy to accommodate these operational realities, ensuring that your barns, heavy equipment, and public-facing farm operations do not leave you financially exposed.
Key Endorsements for Agritourism, Outbuildings, and Equipment
Modern agricultural properties often host diverse revenue streams. From seasonal corn mazes to on-site farm markets, these activities introduce commercial risks that require tailored endorsements.
When structuring your farm policy, consider these critical endorsements:
- Barn and Outbuilding Schedules: Ensures each structure is insured for its actual replacement cost rather than an arbitrary percentage of your house’s value.
- Commercial & Agritourism Liability: Protects your farm if visitors get injured during farm tours, harvest festivals, or seasonal events.
- Equipment Breakdown & Mobile Machinery: Covers expensive tractors, harvesters, and irrigation pumps against mechanical failure, foreign object ingestion, and accidental physical damage.
- Roadside Stand & Farm Market Endorsement: Extends product liability coverage to the food, nursery items, or agricultural goods you sell directly to consumers.
Investing in physical equipment protection – such as dedicated farming supply bundles to protect crops and nursery beds – works hand in hand with insurance to keep your farm operating smoothly year-round.
How to Get and Evaluate a Farm Insurance Bundle Quote
Shopping for a combined insurance policy requires evaluating fine print rather than just looking at the bottom-line price. When you Compare Insurance Quotes Complete Guide, you want to confirm that lower rates are not the result of stripped-away coverage or unreasonably high out-of-pocket deductibles.
To properly evaluate a quote, follow these core steps:
Information Needed for an Accurate Farm Insurance Bundle Quote
To ensure underwriters provide an accurate quote without unexpected mid-term rate adjustments, have the following details ready when requesting Auto Insurance Quotes and property packages:
- Residential Property Details: Square footage, age of roof, primary heating systems, electrical panel updates, and proximity to the nearest fire department.
- Vehicle Information: Vehicle Identification Numbers (VINs), annual mileage, safety features, and primary usage (commuting, farm utility, or commercial hauling) for every vehicle.
- Driver Profiles: Driver’s license numbers, driving histories, and details of all household operators.
- Farm Operations Profile: Acreage owned and leased, types of livestock on-site, crop types, annual agricultural gross revenues, and details on any agritourism activities.
- Structures and Machinery Schedule: An itemized list of barns, outbuildings, tractors, implements, and major mechanical systems, including estimated replacement values and serial numbers.
Assessing Policy Exclusions, Deductibles, and Liability Limits
When reviewing policy quotes, check for specific exclusions that commonly affect rural and agricultural properties:
- Windstorm and Hail Deductibles: Some policies apply separate, percentage-based deductibles for wind or hail damage to roofs and farm structures instead of a flat dollar deductible.
- Single-Loss Deductibles: Look for carriers that offer a single deductible if a single event (like a severe thunderstorm) damages both your home and your personal vehicle at the same time.
- Pollution and Chemical Drift: Standard liability often excludes chemical spray drift (such as pesticides or fertilizers). Check whether an endorsement is included to protect against accidental overspray claims.
- Livestock Ingress/Egress: Verify whether your liability covers damages if livestock escapes onto public roadways and causes an automotive accident.
- Umbrella Liability: Consider adding a commercial or personal umbrella policy to provide higher liability limits above your auto and homeowners baselines.
Real Cost Breakdown and Expected Multi-Policy Discounts
Insurance pricing is influenced by regional weather patterns, local building material costs, and municipal fire protection capabilities. When assessing your overall Homeowners Insurance PA Cost, combining multiple coverages into one package creates measurable savings that help offset broader industry rate increases.
Estimating Savings with a Farm Insurance Bundle Quote
When bundling property, vehicles, and specialized farm endorsements, overall discounts generally range from 10% to 25% off standard unbundled rates. Carriers apply these savings through multiple billing credits:
- Multi-Policy Discount: Applied directly to the dwelling and vehicle premiums for carrying both lines with one insurer.
- Multi-Vehicle Credit: Applied when two or more personal or farm utility vehicles are listed on the same auto policy.
- Claim-Free Renewal Credits: Lower renewal pricing for policyholders who maintain clean loss histories over three to five consecutive years.
- Paid-in-Full & Electronic Billing Discounts: Additional modest reductions (typically 3% to 7%) for paying the annual premium upfront or enrolling in automatic monthly payments.
Bundling Crop, Vehicle, and Property Coverage
For commercial producers, risk management extends into the fields. While Multi-Peril Crop Insurance (MPCI) is federally regulated, private supplemental crop endorsements can often be coordinated alongside your commercial property and vehicle policies through our Home Insurance Quotes Guide 2026.
Supplemental crop packages allow producers to package individual crop protections (such as private hail, wind, early planting, and replant coverage) into a single, cost-effective policy. These supplemental packages deliver tangible premium reductions, such as a 12% discount for corn and a 10% discount for soybeans, while eliminating strict replanting hurdles like the standard 20/20 rule.
Aligning your private crop endorsements, farm equipment schedules, commercial auto, and residential property under a unified insurance strategy gives you comprehensive protection while maximizing your multi-line savings.
Frequently Asked Questions About Bundling Insurance
How much can I save by bundling home and vehicle policies?
Most property owners save between 10% and 25% on their combined annual premiums when bundling personal auto and homeowners policies with a single carrier. Actual dollar savings vary based on your property value, the number of vehicles insured, your driving records, and the specific policy endorsements you choose.
Does bundling protect specialized farm structures and equipment?
A standard personal home and auto bundle does not automatically cover specialized farm outbuildings, commercial barns, or heavy agricultural machinery. To ensure these assets are protected, you must add scheduled agricultural property endorsements, equipment breakdown coverage, or a dedicated farm package to your core bundle.
Can I bundle policies if I have a prior property or auto claim?
Yes. Having a past property or auto claim does not automatically disqualify you from multi-policy bundles. While a recent claim may affect your base rate or remove a claims-free discount, you can still qualify for multi-policy and multi-car savings by placing your coverages with one insurance provider.
Conclusion
Finding the right insurance bundle is about more than just securing a multi-policy discount—it is about making sure your coverage matches your everyday risks. Whether you need straightforward home and auto protection or specialized endorsements for outbuildings, livestock, and farm machinery, bundling helps eliminate coverage gaps while keeping your annual premiums manageable.
At Newtown Insurance, we work with homeowners, vehicle owners, and agricultural operations throughout Pennsylvania to build transparent, cost-effective coverage packages. Connect with our team today to review your existing policies, explore multi-line discount options, and secure a customized quote designed around your property and lifestyle.